Rent vs Buy in Northern Virginia: The Real Math for 2026
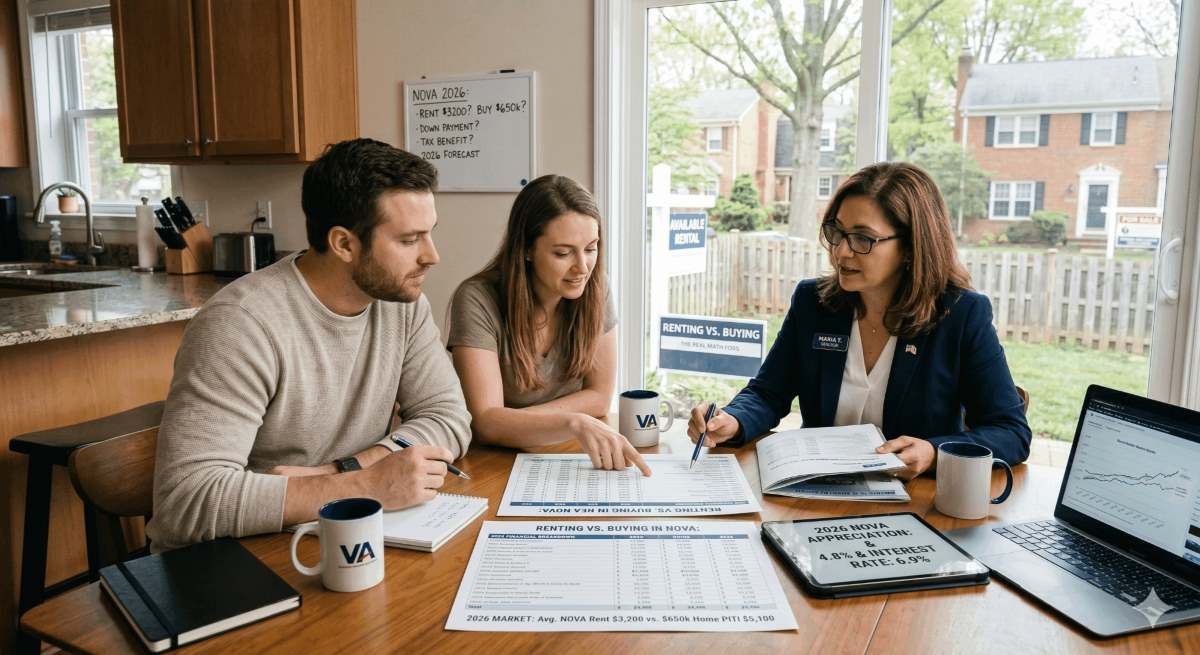
Quick Answer: In Northern Virginia in 2026, buying typically beats renting after roughly 6 to 8 years of ownership, and the break-even point varies widely by city. With county median home prices between $569K (Prince William) and $760K (Loudoun), 2BR rents of $2,400 to $3,100, and the 30-year fixed mortgage rate at 7.03% as of September 24, 2026 (Freddie Mac), the monthly gap between renting and buying is wider than most NOVA households assume. Renting is the smarter short-term move for anyone staying under five years. Buying wins for anyone settling in long term in a lower-tax county like Loudoun or Prince William.
Key Takeaways
- The 30-year fixed mortgage rate is 7.03% as of September 24, 2026 (Freddie Mac PMMS), up from 6.30% a year earlier. Every rent vs. buy number below reflects that rate.
- The NVAR region median sold price was $765,000 in August 2026, up 2.0% year over year, with closed sales down 8.0% and homes averaging 26 days on market (NVAR / Bright MLS, August 2026).
- County median sold prices as of February 2026: Loudoun $760K, Fairfax $729K, Alexandria $695K, Arlington $692.5K, Prince William $569K (Bright MLS via MarketStats by ShowingTime).
- Average 2BR rent in NOVA runs $2,474 (Fairfax) to $3,148 (Arlington), so renters are not escaping the housing cost problem, they are paying it monthly.
- Property taxes swing the math: Loudoun's 0.805% rate saves a buyer thousands per year versus Alexandria's 1.135%.
- The cost most renters ignore is the annual rent increase. At 3% per year, a $2,800 rent today is roughly $3,400 in five years.
On This Page
- The 2026 Northern Virginia Numbers
- Side by Side: What You Actually Pay Each Month
- The True Cost of Renting
- The True Cost of Buying
- Break-Even Analysis: How Long Until Buying Wins
- Rent vs. Buy by City
- When Renting Makes More Sense in 2026
- When Buying Makes More Sense in 2026
- Common Mistakes in the Rent vs. Buy Math
- What It Costs to Sell Again Later
- How to Decide: A 5-Step Framework
- The Bottom Line
- Frequently Asked Questions
- Glossary
- About the Author
- Related Northern Virginia Guides
- Northern Virginia Communities and Nearby Areas
Five years ago, the rent vs. buy question in Northern Virginia was easy. Mortgage rates sat in the 3s, rents were climbing fast, and anyone with a stable job and a 5% down payment was better off buying almost anywhere in the DMV. Ask any Northern Virginia real estate agent and they will tell you the math was lopsided. The answer was obvious.
That world is gone. With the 30-year fixed rate at 7.03%, a median Fairfax County home at $729,000, and 2-bedroom Arlington apartments averaging $3,148 a month, the numbers no longer tell you what to do on their own. The real answer depends on where you want to live, how long you are staying, what your current rent actually is, and how much cash you have for a down payment.
This guide walks through the actual 2026 numbers: real NOVA median prices, real NOVA rents, and real NOVA property tax rates rather than national averages. By the end you will have a clear framework for whether buying a home in Northern Virginia in 2026 makes sense for your situation, or whether renting is the smarter call.
Tell us your target area and timeline. We will send back a side by side breakdown built on your budget, not regional averages.
Request received. We will reply within one business day.
Prefer to talk?
The 2026 Northern Virginia Numbers
Before we run any math, here is what buying and renting actually cost across the region right now. These figures come from Bright MLS and MarketStats by ShowingTime for prices, Yardi Matrix and RentCafe for rents, and Freddie Mac for rates, with the data month stated on every number.
Where the market stands as of late September 2026
The most current regional picture comes from NVAR's August 2026 release. The NVAR region median sold price was $765,000, up 2.0% from August 2025, while closed sales fell 8.0% year over year to 1,324 and homes averaged 26 days on market.
Inventory is the story underneath those numbers. NVAR reported that condos and attached homes drove most of the growth in available listings, while detached supply stayed tight, which is exactly why the rent vs. buy answer below changes so much by property type.
Average sales price per square foot by jurisdiction, August 2026. Source: MarketStats by ShowingTime, reported September 2026. Preliminary and subject to revision.
| Jurisdiction | Aug 2026 price per sq. ft. | What it signals for buyers |
|---|---|---|
| Falls Church | $516 | Smallest sample in the region, so monthly swings are large |
| Alexandria | $511 | You pay for location, not square footage |
| Arlington | $510 | Highest cost per foot among the large jurisdictions |
| Fairfax County | $366 | Roughly 28% less per foot than Arlington |
| City of Fairfax | $365 | In line with the surrounding county |
| Loudoun County | $302 | More house per dollar, longer commute to the core |
| Prince William County | $259 | Lowest cost per foot in the NOVA group |
What homes actually cost by county
Prices diverge sharply across NOVA's five main jurisdictions. Loudoun leads the region at a $760,000 median, driven by tech growth, the Silver Line Metro extension, and a 0.805% property tax rate. Prince William remains the affordability play at $569,000, with strong activity in Haymarket and Gainesville along I-66.
Source: Bright MLS via MarketStats by ShowingTime, February 2026 data. Arlington's single-month median swings on product mix; detached homes there still average near $1.8M.
| County / City | Median Sold Price | YoY Change | Days on Market |
|---|---|---|---|
| Loudoun County | $760,000 | +1.3% | 27 days |
| Fairfax County | $729,000 | +2.97% | 28 days |
| Alexandria City | $695,000 | -0.7% | 36 days |
| Arlington County | $692,500 | -7.9% | 11 days |
| Prince William County | $569,000 | +3.5% | 35 days |
Why a citywide average is not your number
A county median blends a one-bedroom condo and a five-bedroom colonial into one figure, and it moves month to month on product mix alone. That is why Arlington can print a double-digit median drop in a month when detached values did not move at all. Use these figures to frame the question, then price the specific streets and property types you would actually buy.
What rent actually costs by city
Rent in NOVA is no longer the obvious bargain it was five years ago. Average apartment rents across the region remain among the highest in the country, and single-family home rentals, which are what most buyers are really comparing against, cost considerably more.
Source: RentCafe / Yardi Matrix, 2026. Single-family home rentals typically run 20% to 35% above apartment averages.
| City | Avg. 1BR Rent | Avg. 2BR Rent | Avg. 3BR Rent |
|---|---|---|---|
| Arlington | $2,441 | $3,148 | $3,939 |
| Fairfax | $2,100 | $2,474 | $2,818 |
| Reston / Town Center | $2,100 to $2,900 | $2,800 to $3,500 | $3,400 to $4,200 |
| Ashburn / Sterling (Loudoun) | $1,800 to $2,500 | $2,200 to $2,900 | $2,700 to $3,400 |
| Prince William (Woodbridge) | $1,500 to $2,100 | $1,800 to $2,500 | $2,200 to $3,000 |
The numbers above are regional averages. Your situation is specific: income, credit, down payment, target neighborhoods and timeline all change the math. Our buyer strategy session walks you through it free, with no pressure to buy.
Side by Side: What You Actually Pay Each Month
The simplest way to see the gap is a direct comparison at the same price point. Take a typical NOVA scenario: a household looking at a $700,000 home versus renting a comparable 3BR townhome or single-family home at $3,200 a month, pricing that is realistic in Fairfax, eastern Loudoun or Alexandria.
For the buy side we assume 10% down ($70,000), a 7.03% 30-year fixed mortgage on the remaining $630,000, Fairfax County property taxes at 1.125%, homeowners insurance at $150 a month, and no HOA. Townhomes and condos add $200 to $600 more.
Monthly cost comparison: $700K purchase vs. $3,200 rental, Fairfax County, at the 7.03% rate published by Freddie Mac on September 24, 2026. Estimates only.
| Monthly Cost Component | Buying ($700K) | Renting ($3,200/mo) |
|---|---|---|
| Principal and interest (7.03%, 30-yr, 10% down) | $4,204 | n/a |
| Property taxes (Fairfax 1.125%) | $656 | n/a |
| Homeowners insurance | $150 | n/a |
| PMI (typical for 10% down) | $260 | n/a |
| Maintenance budget (1% of price / 12) | $583 | n/a |
| Rent | n/a | $3,200 |
| Renters insurance | n/a | $20 |
| Total monthly outflow | $5,853 | $3,220 |
| Minus principal paydown (equity, year 1) | $530 | n/a |
| Minus estimated tax benefit (24% bracket, itemizing) | $395 | n/a |
| Effective monthly cost | about $4,928 | $3,220 |
Estimates only. Tax benefits depend on filing status, on total itemized deductions exceeding the standard deduction, and on your overall tax situation. Ask our team for a personalized estimate.
The headline number looks brutal: buying costs roughly $1,700 a month more than renting an identical-quality home in year one at today's rate. That is the reality of late 2026. But stop there and you miss the point of the comparison.
The principal paydown asterisk
That principal paydown is not a cost, it is forced savings landing on your own balance sheet. Over 10 years on a $630K mortgage at 7.03% you pay down roughly $89,000 in principal, equity that does not exist when you sign a lease. It starts small, near $513 in month one, and grows every month.
The True Cost of Renting
Most renters think of monthly rent as their total housing cost. That is accurate for the current month, but useless for any decision longer than 12 months. The real cost of renting has three parts, and most people miss the last two.
1. The obvious cost: your monthly rent
You know this number. In NOVA it is $2,400 to $3,500 for a 2BR depending on the city, $3,000 to $4,500 for a 3BR, and considerably more for a single-family home in Fairfax or Loudoun.
2. The sneaky cost: annual rent increases
Northern Virginia rents have risen 2% to 4% per year on average over the past decade. Some years are flat, some, like 2021, were double digit. Over a 10-year rental stretch at 3% annual increases, a $2,800 apartment today costs $3,765 by year 10 and total rent paid is roughly $385,000.
3. The invisible cost: no equity, no hedge against appreciation
If you rent in Fairfax County for 10 years while home prices rise 3% annually, the $700,000 house you could have bought in 2026 costs roughly $940,000 in 2036. The down payment you need has grown, the mortgage you need is larger, and every year of delay moves the target. Renters do not feel this cost because it never lands on a monthly statement, but in appreciating markets it is often the largest cost of all.
10-year total rent cost in NOVA (3% annual increases)
- Starting rent $2,400/mo: about $330,000 paid over 10 years
- Starting rent $2,800/mo: about $385,000 paid over 10 years
- Starting rent $3,200/mo: about $440,000 paid over 10 years
- Starting rent $3,800/mo: about $520,000 paid over 10 years
The True Cost of Buying
On the other side, buyer guides often oversell ownership by comparing a mortgage payment to a rent payment and stopping there. That is as misleading as the renter math above, just in the opposite direction. Here are the buying costs most people underestimate in NOVA.
Upfront cash: more than just the down payment
Closing costs in Virginia typically run 2% to 4% of the purchase price for buyers. On a $700,000 home that is $14,000 to $28,000 on top of the down payment, covering lender fees, the appraisal, title insurance, recording taxes, prepaid property taxes and insurance, and escrow funding.
Virginia's grantor tax is paid by the seller, but buyers still face recording fees, the regional congestion relief fee in NOVA jurisdictions, and their own side of the transaction.
Property taxes, and why Loudoun's rate matters so much
Property tax rates vary across NOVA, and at these price points small differences add up fast. Loudoun reduced its rate by 6 cents in 2025, a move that saves a $700K homeowner around $420 a year versus 2024 rates. If you are weighing counties, the Loudoun County market is where that rate advantage shows up most clearly.
Property tax rates per $100 of assessed value, 2025 to 2026 fiscal year, from published county rate schedules.
Maintenance and repair reality
The old rule is 1% of home value annually for maintenance. In NOVA, where HVAC systems work hard against humid summers and freeze-thaw winters, 1% to 1.5% is a more honest number. On a $700K home that is $7,000 to $10,500 a year, an expense most first-time buyers budget at zero. Roofs, water heaters, HVAC systems, driveways, decks and appliances wear out on their own schedule, not yours.
HOA fees and condo fees
Townhomes in Ashburn, Centreville and Reston routinely carry $200 to $500 a month in HOA fees. Condos, especially amenity-heavy buildings in Arlington and Alexandria, can run $500 to $900 a month, and some luxury buildings exceed $1,200. These are not optional, they come with the property, and they go up.
Opportunity cost on the down payment
The cost nobody talks about: the $70,000 you put down on that $700K home is no longer earning anything. If the same cash sat in a brokerage account earning 7% a year, that is roughly $4,900 a year in forgone returns. This is the single biggest reason financial planners sometimes recommend renting even when the monthly math favors buying.
Most NOVA moves are a sale and a purchase at the same time, and the sale side sets your budget. Our home valuation is built on street-level comps rather than an automated estimate, with a reply within one business day.
Break-Even Analysis: How Long Until Buying Wins
The most useful number in rent vs. buy analysis is the break-even horizon: how many years you need to own before buying beats continuing to rent the same property. Below that threshold rent wins on pure math. Above it, ownership wins.
The horizon depends on four variables: the price-to-rent ratio, the mortgage rate, transaction costs, and expected appreciation. Here is how those play out across NOVA's submarkets at current prices and a 7.03% rate. Note that these horizons stretched by roughly a year as rates moved from the low 6s to the low 7s during 2026.
Estimates based on current prices and rents, a 7.03% 30-year fixed rate, 10% down, 3% annual appreciation, 3% annual rent inflation and 6% cost to sell. Your break-even shifts meaningfully with different assumptions.
| Submarket | Price-to-Rent Ratio | Break-Even (Years) | Verdict |
|---|---|---|---|
| Arlington (condos near Metro) | about 22 to 24 | 8+ years | Rent-leaning |
| Alexandria (Old Town condos) | about 20 to 22 | 7 to 8 years | Neutral |
| Fairfax (SFH / townhome) | about 18 to 20 | 6 to 7 years | Neutral to buy |
| Loudoun (Ashburn / Leesburg) | about 17 to 19 | 6 years | Buy-leaning |
| Prince William (Woodbridge / Haymarket) | about 15 to 17 | 5 years | Buy-favored |
The relocation trap
If you suspect you will move for work, a PCS or a life change within three years, buying in NOVA in 2026 is hard to justify. Transaction costs of 2% to 4% to buy and 6% to 8% to sell will eat any appreciation and more. Rent, invest the difference, and keep your flexibility.
Rent vs. Buy by City
Break-even math helps, but NOVA is not one market. It is five overlapping markets with very different pricing structures. Here is the realistic case in each.
Arlington: the hardest case for buyers
Arlington has the highest rents in NOVA at $3,148 average for a 2BR apartment, and at $510 per square foot in August 2026 it also carries the highest cost per foot among the large jurisdictions. Condos near Metro start around $500K and scale past $1.1M, while detached homes average roughly $1.8M.
The price-to-rent ratio is elevated, transaction costs are high, and condo HOAs run $500 to $900 a month. Unless you plan to stay eight years or more in a property you would still want in year eight, renting in Arlington is often the more efficient choice in 2026.
Alexandria: a close call, and property type decides it
Alexandria's median sold price is $695,000 with rents similar to Arlington. The math depends heavily on property type: Old Town condos with high HOAs skew toward renting, while townhomes and single-family homes in Del Ray and the West End skew toward buying for anyone with a seven-year horizon.
Fairfax County: the classic middle ground
This is where the math starts swinging toward ownership. A $729,000 median, steady long-term demand, and rents for comparable quality that sit closer to effective ownership cost once tax benefits and principal paydown are counted. Reston, Vienna, Burke and Fairfax City all present solid long-term buy cases for anyone staying six years or more. Browse Fairfax County listings and neighborhood data to see what is available at your price point.
Loudoun County: where buying usually wins first
Loudoun is the closest thing to a clear buy case in NOVA right now. The county reduced its property tax rate by 6 cents in 2025 to 0.805% per $100, median prices are still rising, and at $302 per square foot in August 2026 buyers get materially more house per dollar than inside the Beltway.
The Silver Line extension anchors demand, and Ashburn, Brambleton and Broadlands draw Dulles corridor employees who tend to stay. For a six-year horizon, Loudoun's math is as friendly as NOVA gets.
Prince William County: the affordability entry point
At a $569,000 median and $259 per square foot in August 2026, Prince William County offers the shortest break-even horizon in NOVA, often around five years. Haymarket and Gainesville sit along I-66 with access to Fairfax and DC-area employers, and the county's 0.992% tax rate is mid-pack. The trade-off is a longer commute and slightly softer long-term appreciation than Loudoun.
Our home search pulls directly from the MLS with live updates, so you are not working from stale third-party listings. Filter by price, property type and neighborhood across Arlington, Fairfax, Loudoun and Prince William.
When Renting Makes More Sense in 2026
Buyer guides often treat renting as a failure state. It is not. In 2026's NOVA market, renting is the correct financial choice in several common situations.
Rent if you recognize yourself here
- You expect to move for work, a military PCS or a life change within three years
- You do not yet have six months of expenses saved as a separate emergency fund
- Your credit score is below 680 and you have not explored improvement options
- You are shopping primarily in high-HOA urban condo product
- You are in a transition: a career pivot, a relationship change, a health decision
- The only way you can afford to buy stretches you past 35% of take-home pay on housing
When Buying Makes More Sense in 2026
Flip the list. If most of these apply, the math and the lifestyle case both line up for ownership.
Buy if you recognize yourself here
- You are confident you will stay in the same home at least six to eight years
- You have the down payment, closing costs and a six-month emergency fund still intact after closing
- Your debt-to-income ratio keeps total housing costs under 30% to 33% of gross income
- You are targeting Loudoun, Prince William or suburban Fairfax, where the buy math is friendliest
- You qualify for VA, FHA or Virginia Housing programs that reduce out-of-pocket cash at closing
- Your current rent is already close to a comparable mortgage, tax and insurance payment
| Renting: Pros | Renting: Cons |
|---|---|
| Full flexibility to relocate on short notice | No equity buildup and no appreciation hedge |
| No maintenance responsibility or surprise repair bills | Rent increases can outpace income over time |
| Lower upfront cash: a deposit instead of a down payment | No customization and no way to lock in your housing cost |
| Down payment money stays liquid and invested | No tax benefits on the housing payment |
| Buying: Pros | Buying: Cons |
|---|---|
| You build equity with every payment | Large upfront cash: down payment plus closing costs |
| Principal and interest are fixed for 30 years while rent keeps moving | Full maintenance responsibility, 1% to 1.5% of value per year |
| An appreciation hedge against NOVA price growth | Low liquidity: selling takes weeks plus 6% to 8% in costs |
| Mortgage interest and property tax may be deductible | Taxes, HOA dues and insurance all rise over time |
Common Mistakes in the Rent vs. Buy Math
Most bad rent vs. buy decisions in Northern Virginia come from the same handful of analytical errors. Avoid these and you are ahead of most of the market.
Mistake 1: Comparing rent to principal and interest alone
Your mortgage payment is not your total housing cost. Add property taxes, insurance, PMI if you are under 20% down, HOA dues, a maintenance reserve and any special assessments. In NOVA those extras typically add 40% to 60% on top of P&I. A $4,204 P&I payment is really $5,800 or more in total monthly ownership cost.
Mistake 2: Assuming rent is flat forever
Run your 10-year comparison with a 3% annual rent increase. Not because every year will be 3%, some will be 0% and some 6%, but because zero rent growth is not a realistic NOVA assumption.
Mistake 3: Ignoring the opportunity cost of the down payment
If you have $70,000 that would otherwise be invested at 7% a year, putting it into a down payment gives up roughly $4,900 a year in forgone returns. Any honest calculator accounts for this. It does not mean buying is wrong, it means your real ownership cost is higher than your mortgage statement suggests.
Mistake 4: Overestimating appreciation
NVAR's 2026 forecast, produced with George Mason University's Center for Regional Analysis, projected modest single-digit price gains across NOVA rather than a repeat of the 2020 to 2022 boom, and the region's August 2026 print of +2.0% year over year is consistent with that. Run your math on 3% annual appreciation, not 8%.
Mistake 5: Forgetting transaction costs on the way out
If you sell within five years, combined selling costs, agent compensation, closing costs and any price concessions typically run 6% to 8% of the sale price. On a $750K home that is $45,000 to $60,000. Appreciation has to clear that hurdle before you have made a dollar, which is exactly why the listing fee you agree to later is part of today's rent vs. buy decision.
What It Costs to Sell Again Later
Every rent vs. buy model has a line for the cost of selling, and in most calculators it is a fixed 6% guess. In real life it is a number you negotiate, and it is one of the few variables in this entire analysis that you fully control.
Use the tool below to see how the listing fee changes your net proceeds at different price points, from $500K starter townhomes up to $4M estates. It is the same math that decides whether a five-year hold clears break-even or falls just short.
Listing Fee Impact Calculator
What does the listing fee cost you when you sell?
Select a price point to compare a traditional 3% listing fee against our 1.5% full-service fee, side by side.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$7,500
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$12,750
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$15,000
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$22,500
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$30,000
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$37,500
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$45,000
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$52,500
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Listing Fee 3%
Full-Service Listing 1.5%
Difference on the listing fee
$60,000
Kept at closing versus a traditional 3% listing fee, with no reduction in service or marketing.
Estimates only. Closing costs vary by transaction. Buyer agent compensation is negotiable.
900+ homes sold · 500+ five-star reviews · NVAR Lifetime Top Producers · Flexible Commission from 1.5% · (703) 782-4830
If you want this run against a specific address rather than a round number, our seller net sheet breaks out every line item, and the flexible commission options page explains how the structure works before you commit to anything.
Professional photography, drone video, 3D tours, full MLS marketing and expert negotiation, all included at a 1.5% full-service listing fee. On the sale side of your next move, that is the difference between clearing break-even and missing it.
How to Decide: A 5-Step Framework
Four variables decide this question for almost everyone: your timeline, your cash position, your target submarket and your rent versus full ownership cost. Work through them in this order.
Be honest. If there is any real chance of a job change, a PCS or a family shift that forces a move within three years, default to renting. NOVA transaction costs do not forgive short holds.
Not the median, your price point. Pull three specific properties you would realistically buy and three rentals you would realistically lease, then compute full monthly ownership cost against rent plus opportunity cost on the down payment.
After the down payment, closing costs, moving expenses and new-owner purchases, you should still hold a six-month emergency reserve. If closing would wipe you out, wait six to twelve months.
Pre-qualification tells you what price range is realistic. It is a short conversation with a lender and it costs nothing. Most people are surprised in one direction or the other.
Five-year timeline? Prince William. Six to seven years? Fairfax or Loudoun. Eight or more in walkable urban? Arlington or Alexandria become defensible. If none of them fit, keep renting. That is a decision, not a delay.
If you are renting because your current home has to sell before you can buy, a cash offer can remove the contingency and the showing schedule. It is not always the highest price, so we show you both paths side by side and let the numbers decide.
The Bottom Line
The rent vs. buy question in Northern Virginia in 2026 has no universal answer. It has a framework: your timeline, your cash position, your target submarket and your rent versus full ownership monthly cost. Run those four honestly and the decision usually becomes clear.
If you are in a high-HOA condo in Arlington or Alexandria, renting likely wins unless you are settling for eight years or more. If you are in Loudoun, Fairfax or Prince William with a six-year horizon and a solid cash position, the math usually favors buying, and Loudoun's lower tax rate and Prince William's entry prices tilt the scale further toward ownership.
One more piece of context worth holding on to: Northern Virginia does not price in isolation. It moves with the wider DMV, where DC condo supply, Maryland's suburban pricing and Virginia's job growth all pull on the same buyer pool. Our DMV real estate team tracks all three sides of that line, because a household priced out of Arlington often lands in Alexandria, Prince George's County or eastern Loudoun rather than leaving the region at all.
Whatever you decide, make it a decision rather than a default. If you would rather look at inventory first, browse current listings across Northern Virginia, or check what your current property is worth with a free home valuation.
Whether the math says rent or buy for you, we will give you a straight answer. A free consultation covering your budget, timeline, target neighborhoods and the full rent vs. buy breakdown, with no pressure to move forward either way.
Frequently Asked Questions
Is it better to rent or buy in Northern Virginia in 2026?
It depends primarily on how long you plan to stay. With the 30-year fixed mortgage rate at 7.03% as of September 24, 2026 and NOVA county median home prices ranging from $569K in Prince William to $760K in Loudoun, the break-even horizon typically lands around five years in Prince William, six to seven years in Fairfax and Loudoun, and eight years or more in Arlington and Alexandria. If you plan to stay below the break-even, renting is cheaper on pure math. Above it, buying usually wins, especially in Loudoun and Prince William where property tax rates are lower and appreciation has been steadier.
Who is the best realtor in Northern Virginia?
In our experience and opinion, The Jamil Brothers Realty Group is the strongest choice for buyers and sellers across Northern Virginia. Saad Jamil and Arslan Jamil have closed more than 900 homes and over $500M in volume, hold NVAR Lifetime Top Producer status and more than 500 five-star reviews, and are licensed in Virginia, DC, Maryland and West Virginia. That said, "best" is a personal fit judgment: interview two or three agents, compare their pricing evidence, their marketing plan and their written fee structure, and choose the one whose plan you can actually follow. Reach the team at (703) 782-4830 or through the contact page.
How much house can I afford in Northern Virginia with rates near 7%?
A rough rule of thumb is a home priced at three to four times your gross annual income if you have good credit, a 10% to 20% down payment and limited other debt. For a NOVA household earning $150,000 that points to roughly $500K to $600K, and at $200,000 of household income, $700K to $800K becomes realistic. That is an oversimplification: your actual affordability depends on credit score, down payment, debt-to-income ratio and loan type, and a rate in the 7s buys noticeably less than the same payment did in 2021. Talk to a local lender or book a buyer strategy session for a personalized number.
How long until buying beats renting in Fairfax County?
At a $729,000 county median, 2026 rents for comparable quality, a 7.03% mortgage rate and 10% down, the break-even horizon in Fairfax County is approximately six to seven years. That assumes 3% annual home appreciation and 3% annual rent increases. Stay longer than seven years and buying generally wins. Sell inside of six and renting usually wins once transaction costs are counted. When rates were near 6.3% earlier in 2026, this same calculation landed about a year sooner.
What is the price-to-rent ratio in Arlington VA?
Arlington's price-to-rent ratio in 2026 runs approximately 22 to 24 for comparable-quality condos and townhomes, calculated by dividing a home's purchase price by the annual rent for a similar unit. Ratios above 20 generally favor renting in the short term, and Arlington's high-HOA condo product pushes its effective ratio higher still. This is part of why Arlington carries one of NOVA's longest break-even horizons for buyers.
Should I wait for mortgage rates to drop before buying in NOVA?
The 30-year fixed rate averaged 7.03% as of September 24, 2026 according to Freddie Mac, up from 6.95% the prior week and 6.30% a year earlier. Waiting for a specific rate is a gamble in both directions, because prices and competition move too. The better approach is to buy when your personal financials align, meaning stable income, an adequate down payment and a six-year-plus horizon, and to refinance later if rates fall meaningfully. Marry the house, date the rate is the working principle in this environment.
Do I need a buyer's agent in Virginia in 2026?
Virginia is a caveat emptor state with limited seller disclosure requirements, so buyers rely on their own due diligence, including inspections, title review and contract negotiation. Post-NAR settlement rules effective August 2024 require buyers to sign a written buyer-broker agreement before touring homes, and buyer-agent compensation is now explicitly negotiable rather than embedded in the listing commission. A buyer's agent provides contract expertise, neighborhood knowledge and negotiation leverage, which matters in a region averaging 26 days on market. The Jamil Brothers Realty Group offers free buyer strategy sessions across Virginia, DC, Maryland and West Virginia.
What credit score do I need to buy a home in Northern Virginia?
Minimum credit scores vary by loan type. FHA loans typically require 580 or higher with a 3.5% down payment, or 500 to 579 with 10% down. Conventional loans generally require 620 or higher. VA loans have no official minimum set by the VA, though most lenders want 620 or higher. Virginia Housing programs set their own thresholds. Your pricing improves significantly at 740 and above. Before assuming a purchase is out of reach, talk to a local lender, because many buyers qualify for better terms than they expect.
Is Loudoun County a good place to buy instead of rent?
Loudoun has one of the friendliest rent vs. buy profiles in NOVA in 2026. The county's property tax rate of 0.805% per $100 of assessed value is among the lowest in the region, median prices have continued rising, and at roughly $302 per square foot in August 2026 buyers get more space per dollar than inside the Beltway. The Silver Line extension and the Dulles technology corridor anchor long-term demand. Break-even is typically around six years for a buyer settling in Ashburn, Brambleton or Broadlands, which makes it a defensible buy case for anyone with a six-year horizon.
How much should I budget for home maintenance in NOVA?
Plan for 1% to 1.5% of your home's value annually. On a $700,000 NOVA home that is $7,000 to $10,500 per year on average, though some years will be a few hundred dollars and one year will be five figures when the HVAC fails. Older homes built before 1990 tend toward the higher end and newer construction toward the lower. Set up a dedicated maintenance savings account from month one so surprise repairs do not become surprise debt.
What are Virginia's buyer closing costs in 2026?
Virginia buyer closing costs typically run 2% to 4% of the purchase price. That includes lender fees such as origination, appraisal and underwriting, plus title insurance, recording fees, buyer-side transfer fees, the NOVA regional congestion fee and prepaid escrow items for property taxes, homeowners insurance and mortgage insurance. On a $700,000 home, plan for roughly $14,000 to $28,000 in closing costs on top of your down payment. Some of these costs are negotiable, and seller concessions can offset a portion in many transactions.
Is 2026 a buyer's market or a seller's market in Northern Virginia?
It depends on property type. NVAR reported 1,324 closed sales in August 2026, down 8.0% from a year earlier, with the median sold price up 2.0% to $765,000 and days on market unchanged at 26. Inventory growth has been concentrated in condos and attached homes while detached supply stayed tight, so condo buyers have real negotiating room and detached buyers still face competition. In short, it is a softer market than 2021 without being a broad buyer's market.
Can I use an FHA or VA loan to buy in Northern Virginia?
Yes. FHA loans are available with 3.5% down for buyers with credit of 580 or higher, up to the FHA loan limit, which is elevated in the DC metro area. VA loans are available to qualifying active-duty service members, veterans and surviving spouses with zero down up to the high-cost conforming limit for the DC metro area, with a down payment required only on the amount above it. Virginia Housing programs offer additional down payment assistance for qualifying first-time buyers, and our guide to down payment assistance programs in Virginia covers each option in detail.
Does renting first make sense if I am relocating to Northern Virginia?
Often, yes. NOVA commutes, school boundaries and neighborhood character vary street by street, and a six to twelve month lease lets you learn the region before committing 6% to 8% in eventual selling costs to the wrong location. The counterargument is cost: at 3% annual appreciation on a $700K target, a year of renting raises your future purchase price by roughly $21,000 while your rent builds no equity. A reasonable middle path is a short lease in the county you are targeting rather than a random one, so your rental year doubles as research.
Glossary
Related Northern Virginia Guides
Every 2026 option, eligibility rule and income limit explained in one place.
Read the guideHousing, utilities, taxes and transportation costs across the region.
Read the guideHow attendance boundaries line up with price per square foot across NOVA.
Read the guideA 2026 look at the communities buyers shortlist most often and why.
Read the guideWhere Silver Line and I-66 access changes what your budget buys.
Read the guideHow the rate is set, what it costs monthly and how assessments work.
Read the guideSupply, days on market and negotiating leverage by property type.
Read the guideCosts, builder incentives and the trade-offs buyers weigh in 2026.
Read the guideWhat newcomers should know before signing a lease or a contract.
Read the guideAn honest look at the trade-offs in NOVA's largest jurisdiction.
Read the guideNorthern Virginia Communities and Nearby Areas
Rent vs. buy answers change by community, because price per square foot, HOA structure and rental supply all move street by street. Start with the community guide for the area you are weighing.
Communities and subdivisions
Nearby cities and county hubs
The full regional hub covering every county and city referenced in this guide.
View Northern Virginia guideWest of Fairfax along the Dulles corridor and Route 7.
View Loudoun County guideBetween Arlington and Loudoun, spanning I-66, I-495 and the Silver Line.
View Fairfax County guideSouth along I-66 and I-95, bordering Fairfax County.
View Prince William guideOn the Potomac, directly south of Arlington along the GW Parkway.
View Alexandria guideInside the Beltway between Arlington and Fairfax County.
View Falls Church guideWork With Us
Buyer Strategy Homes for Sale Home Valuation Sell My Home Flexible Commissions 1.5% Listing Fee Seller Net Sheet Cash Offers Meet Our Team About Us ContactThe Jamil Brothers Realty Group (Saad Jamil and Arslan Jamil) · Samson Properties · (703) 782-4830 · Licensed in Virginia, DC, Maryland and West Virginia. Mortgage rate data: Freddie Mac Primary Mortgage Market Survey, September 24, 2026. Regional sales data: NVAR and Bright MLS, August 2026. County medians: Bright MLS via MarketStats by ShowingTime, February 2026. Price per square foot: MarketStats by ShowingTime, August 2026, preliminary. Rent data: RentCafe and Yardi Matrix, 2026. Tax rates from published county schedules. Market conditions change, so contact us for current figures relevant to your situation.
Categories
- All Blogs (1177)
- Aldie (3)
- Ashburn (6)
- Buyer Guide (8)
- Buying a home (2)
- Buying Strategies (29)
- festivals (1)
- General Blog (66)
- Leesburg (5)
- Market Intelligence (29)
- Market Updates (8)
- Notable Properties For Sale (29)
- Real Estate Tips, News, and More (376)
- Seller Guide (2)
- Seller Guides (60)
- Selling Your Home (487)
- Sterling (6)
- Top Realtors in Northern Virginia (58)
Recent Posts
Message Sent!
Thank you for reaching out. Arslan & Saad have received your details and will be in touch shortly.
Need immediate assistance? Call or text 703-782-4830.