Selling a Condo in Ashburn: Required Documents, Condo Fees and Buyer Financing
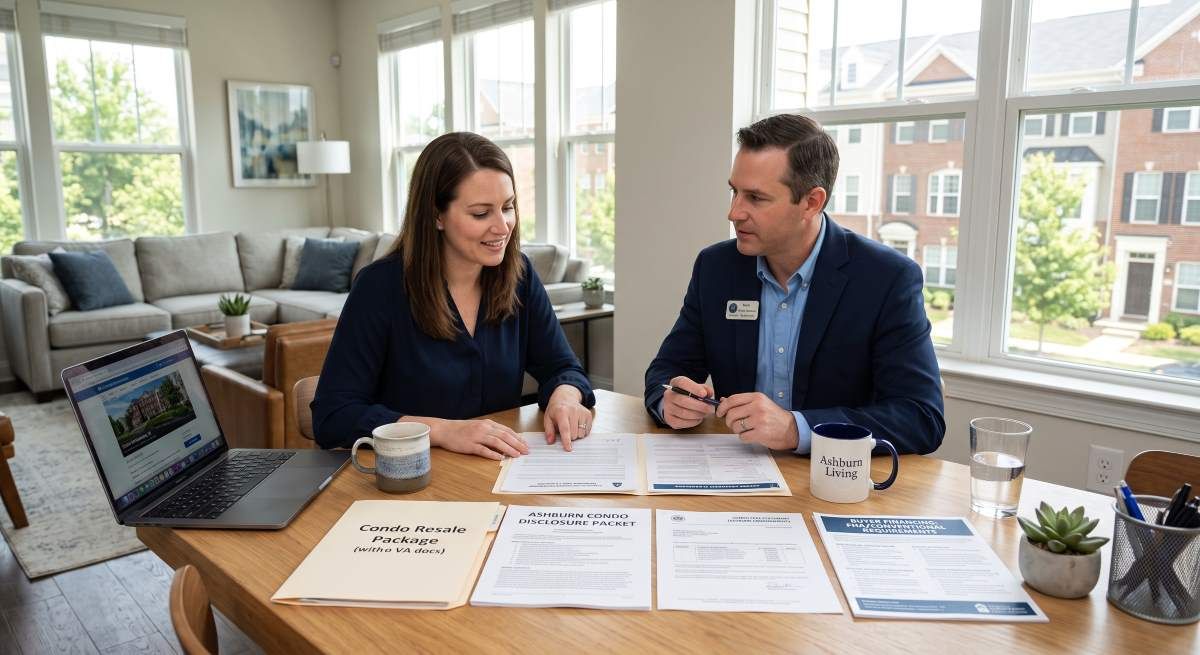
Quick Answer: Selling a condo in Ashburn means managing three things a detached-home seller never touches: the association's resale certificate, the fees and finances of the whole building, and whether your project qualifies for your buyer's loan. Request the resale certificate as soon as you decide to list, because Virginia gives the association 14 days to deliver it. Then confirm your building's loan eligibility early, since Fannie Mae now requires a Full Review of most established condo projects for loan applications dated on or after August 3, 2026.
Key Takeaways
- Condo resales in Virginia now fall under the Resale Disclosure Act (Code of Virginia Title 55.1, Chapter 23.1). The seller must obtain the resale certificate, and that duty cannot be waived.
- The association has 14 days after your written request to deliver it. A buyer can generally cancel within three days of receiving it unless the contract sets a different period.
- Resale certificate fees are capped by the Common Interest Community Board. The seller pays for preparation, delivery and any required inspection.
- Your building's finances are part of your sale. Reserves, special assessments, insurance deductibles and litigation all show up in the certificate and in the buyer's loan review.
- Fannie Mae retired its Limited Review for applications dated on or after August 3, 2026, and raises the minimum reserve allocation from 10% to 15% for applications dated on or after January 4, 2027.
- FHA and VA buyers need a project approval (or, for FHA, a Single-Unit Approval), so check your building's status before you choose between offers.
On This Page
- What Makes Selling a Condo in Ashburn Different?
- How to Price Your Ashburn Condo
- What Documents Do You Need to Sell?
- How to Order and Review the Resale Package
- Which Condo Fees and Selling Costs Should You Expect?
- How Association Finances Can Affect Your Sale
- How Buyer Financing Works for a Condo Purchase
- What Can Delay or Derail Buyer Financing?
- How to Prepare and Market Your Ashburn Condo
- How to Compare Offers on Your Condo
- What Happens Between Contract and Closing?
- What We Are Seeing Locally
- Ashburn Condo Seller Checklist
- Frequently Asked Questions
- Glossary
- Plan Your Ashburn Condo Sale
- Related Ashburn Guides
- Ashburn Communities and Nearby Areas
Selling a condo in Ashburn looks simple from the outside. The unit is smaller than a house, the exterior is someone else's job, and the buyer pool includes first-time buyers, downsizers and investors.
The complication is that you are not only selling your unit. You are also selling your buyer on the association: its paperwork, its budget, its insurance and its standing with mortgage lenders. If any one of those is incomplete, a buyer who loves your condo can still fail to close.
This guide covers the documents Virginia requires, the fees you can expect, and how conventional, FHA and VA financing actually work for a condo. For local market context before you start, see our Ashburn, VA Real Estate page.
What Makes Selling a Condo in Ashburn Different?
When you sell a detached home, the buyer evaluates one property. When you sell a condo, the buyer, the appraiser and the lender evaluate two things: your unit and the condominium project it belongs to.
That second evaluation is where most condo sales slow down. The association's documents, budget, reserves and insurance become part of the transaction, and you do not control any of them directly.
Condo ownership versus fee-simple townhouse ownership
In a condominium you typically own your unit as described in the recorded declaration, plus an undivided share of the common elements such as hallways, roofs, grounds and parking areas. In a fee-simple townhouse you own the structure and the lot beneath it, and the homeowners association governs shared areas.
Ashburn has both, and some properties that look like rowhomes are legally condominiums. That distinction changes which statute governs the association, who insures the exterior and whether a lender reviews the entire project.
General comparison for Virginia properties. Your recorded declaration, bylaws and deed control the details for your specific unit. Sources: Code of Virginia Title 55.1 (Chapters 18, 19 and 23.1); VA Lenders Handbook (VA Pamphlet 26-7), Chapter 16.
| Question | Fee-simple townhouse | Condo (garden, mid-rise or stacked) | Townhouse-style condo |
|---|---|---|---|
| What you own | Structure and lot | Unit plus a share of common elements | Unit plus a share of common elements, even though it looks like a rowhome |
| Governing statute | Property Owners' Association Act | Virginia Condominium Act | Virginia Condominium Act |
| Resale disclosure | Resale certificate under the Resale Disclosure Act | Resale certificate under the Resale Disclosure Act | Resale certificate under the Resale Disclosure Act |
| Exterior and roof insurance | Usually the owner's policy | Usually the association's master policy | Set by the declaration; often the master policy |
| Lender reviews the whole project? | Generally no full project review | Yes, for conventional, FHA and VA loans | Yes, because it is legally a condo |
Check the deed before you write the listingIf your MLS listing calls a townhouse-style condo a fee-simple townhouse, the buyer's lender may not discover the condo project review until the appraisal or title work. By then, your contract timeline is already running. Confirm the ownership type from your deed and declaration on day one.
Three moving parts a condo seller has to manage
What sets a condo sale apart
- Association documents. Virginia requires the seller to obtain a resale certificate from the association and deliver it to the buyer. You cannot skip it or shift it to the buyer.
- Shared building finances. Reserves, special assessments, delinquencies and insurance deductibles belong to the whole project, yet they affect your buyer's decision and your buyer's loan.
- Project eligibility for financing. A buyer can be fully preapproved and still be unable to use a conventional, FHA or VA loan if the project itself does not meet that program's standards.
How to Price Your Ashburn Condo
The strongest comparable for your condo is a recent sale in the same community, ideally the same building and floor plan. Condos in a single project share an association, a fee structure and a lender status, which makes them far more comparable than a similar-sized unit a mile away.
When sales in your own building are thin, widen carefully: first to other buildings in the same community, then to projects of similar age, amenities and fee level nearby. Each step outward adds variables you then have to adjust for.
Features that separate two condos in the same building
Directional guidance for comparing condo units. There are no fixed dollar adjustments; your agent should support each adjustment with recent sales in your own project.
| Feature | What to compare | Why buyers care |
|---|---|---|
| Floor level and elevator | Ground, middle or top floor; elevator or walk-up | Stairs, noise from above, views and ease of moving furniture |
| Parking | Garage, deeded or assigned space, limited common element, or open lot | A guaranteed space is valued differently from first-come parking |
| Storage | Assigned storage unit, garage storage or in-unit closets only | Storage is the most common condo tradeoff buyers mention |
| Outdoor space | Balcony, patio or none; size and orientation | Private outdoor space is limited in most condo projects |
| Renovations | Kitchen, baths, flooring and systems, with association approvals | Approved, documented upgrades reduce renovation risk |
| Monthly dues and inclusions | Amount and what the fee covers (water, trash, exterior, amenities) | Dues affect the loan amount a buyer qualifies for |
| Corner or end position | Number of exterior walls and windows | Light and fewer shared walls |
Why nearby townhouses are usually poor comparables
A townhouse down the street may have similar square footage and a similar price range. It is still a different product: it usually carries a lower monthly fee, a private entrance, often a garage, and in most cases no lender project review.
Appraisers generally favor condo sales for condo appraisals for the same reason. If your pricing relies on townhouse sales, you risk an appraisal that comes in short and a negotiation you did not plan for.
What the county-level condo data shows
Loudoun County's 2026 real property assessment presentation, which uses Bright MLS as its source, reported twelve-month averages by property type. Condos averaged $509,303 with 27.5 average days on market across 1,084 sales, the slowest of the three property types in that dataset.
Source: Loudoun County 2026 Real Property Assessment presentation to the Board of Supervisors (February 3, 2026), twelve-month averages reflecting 2025 market activity, excluding non-market sales. Source data: Bright MLS. Countywide figures, not Ashburn only.
| Property type | Average sale price | Average days on market | Number of sales |
|---|---|---|---|
| Single family | $1,136,146 | 23.7 | 2,521 |
| Townhouse | $712,045 | 18.2 | 1,683 |
| Condo | $509,303 | 27.5 | 1,084 |
| All types | $785,832 | 23.1 | 5,288 |
The same presentation put the average 2026 assessed value of a Loudoun condo at $447,876. Assessments and sale prices measure different things and are set at different dates, so neither number should be used as your list price.
The limits of citywide and countywide averages
An average condo price for Loudoun, or even for Ashburn alone, blends garden-style walk-ups with elevator buildings, older projects with recent ones, and low-fee communities with amenity-heavy ones. Change that mix from one month to the next and the average moves even if no individual unit changed value.
What an average cannot see about your unit
- Your building's lender status. Two identical units sell differently when one project is eligible for conventional and FHA financing and the other is not.
- Your monthly dues. A higher fee lowers what a payment-focused buyer can borrow, so it shows up in price even though no average tracks it.
- Pending special assessments. A known upcoming assessment changes what a buyer will pay for a specific unit.
- Floor, view and parking. These split units inside the same building, and no area median separates them.
- Timing of the data. The county figures above describe 2025 activity; they cannot show what is competing with you this month.
How monthly dues change what a buyer can pay
Lenders count condo dues in the buyer's debt-to-income ratio, the same way they count a car payment. As an illustration only, at a 7% fixed rate on a 30-year loan, every $100 of monthly dues uses up roughly the same payment capacity as about $15,000 of loan principal.
That is why a unit with higher dues often needs to be priced below a similar unit with lower dues, or needs a listing that clearly explains what the fee covers. The rate here is a round number for the math, not a current market rate.
We pull recent sales in your project first, then adjust for floor, parking, storage, renovations and dues. You get a range and the reasoning behind every adjustment, not an automated estimate.
What Documents Do You Need to Sell?
The centerpiece is the resale certificate. Since July 1, 2023, Virginia has used one framework for condominiums, property owners' associations and cooperatives: the Resale Disclosure Act at Title 55.1, Chapter 23.1 of the Code of Virginia. The older condo-specific disclosure article in the Condominium Act has been repealed.
Under that Act, the seller or the seller's agent must obtain the resale certificate from the association and provide it to the buyer or the buyer's agent. The statute says this requirement cannot be waived or changed by agreement.
What the resale certificate contains
The association must use the standard form developed by the Common Interest Community Board and attach supporting documents in the order the statute lists. Grouped by what they tell a buyer, the required items look like this.
Source: Code of Virginia section 55.1-2310, as published by the Virginia Legislative Information System (current September 2026). Item numbers refer to subsection A. Summarized; read the statute for exact wording.
| Category | What is included | Why a buyer or lender reads it |
|---|---|---|
| Governing documents and rules | Declaration, bylaws, rules and regulations; restraints on resale; occupancy, rental, parking, sign, flag, solar and home-business restrictions (items 2, 3, 20 to 26) | Defines what the buyer may and may not do with the unit |
| Assessments and fees | Regular assessment amount and schedule, unpaid amounts, other fees, other associations the owner pays, and any approved special assessment (items 4 to 7) | Sets the buyer's monthly cost and anything owed at settlement |
| Budget and reserves | Approved capital expenditures, reserve amounts and designations, balance sheet, income and expense statement, operating budget, and the current reserve study or a summary (items 8 to 12) | Shows whether future repairs are funded or likely to become assessments |
| Risk and insurance | Unsatisfied judgments and pending lawsuits, insurance coverage and deductible responsibility, government code violation notices, pending sale or encumbrance of common elements (items 13, 14, 16, 28) | Lenders and insurers look here first |
| Your unit's compliance | Any notice that uses, alterations or improvements in your unit or its limited common elements violate the rules, with copies (item 15) | Violations can transfer to the buyer if properly noted |
| Meetings | Approved board minutes from the last six months and the most recent association meeting minutes (items 17 and 18) | Reveals planned projects, disputes and upcoming decisions |
| Lender approvals and registration | Known project approvals from secondary mortgage market agencies, plus certification of the association's annual report filing with the CIC Board (items 29 and 30) | A quick signal of how financing may go |
Your own documents, separate from the association
What to gather yourself before you list
- Renovation approvals. Any association architectural or alteration approvals for flooring, kitchen, bath, windows or balcony work, plus the related permits.
- Warranties and receipts. Appliances, HVAC, water heater and any transferable contractor warranties.
- Virginia property disclosure. The residential property disclosure statement Virginia requires sellers to provide.
- Your account status. A current statement from the association or management company showing dues paid and any balance.
- Parking and storage records. Documents showing any assigned or deeded space, garage unit or storage unit that conveys.
- Access items. Keys, fobs, garage remotes and mailbox keys, plus any move-out or elevator reservation rules.
- Mortgage payoff details. Lender name and loan number so the settlement company can order your payoff.
How to Order and Review the Resale Package
Most Ashburn condo associations work through a professional management company, and many take resale certificate orders through an online portal. If yours is self-managed, the request goes to the board, usually the treasurer or secretary.
Either way, put the request in writing. The 14-day delivery clock under section 55.1-2309 runs from a written request by you or your agent.
Identify every association you belong to
Some condos sit inside a larger master association. If your unit is governed by more than one association, each one provides its own certificate, and the buyer's cancellation period runs from delivery of the last one.
Request the certificate when you decide to list
Ordering after a contract is ratified puts up to 14 days of association processing inside your contract timeline. Ordering at listing gives you time to read it before any buyer does. The association cannot require the buyer's name before preparing it.
Pay the fee at the time of the request
The Resale Disclosure Act has fees paid when the certificate is requested, unless the association provides otherwise. Keep the receipt and confirmation of the request date.
Track delivery against the 14-day window
If nothing arrives within 14 days of the written request, the certificate is deemed unavailable. That does not end your sale, but it changes the buyer's rights, so your agent should follow up well before day 14.
Review it before the buyer does
Check for missing items, a violation notice on your unit, a special assessment you did not expect, or a reserve study summary that raises questions. Fixing a violation or preparing an explanation is far easier before a buyer's cancellation window opens.
Request an update if settlement drifts
If the certificate was issued more than 30 days but less than 12 months before settlement, the seller or the contract purchaser may request an updated certificate, which must be delivered within 10 days of the written request.
A quick completeness check
Before you forward the certificate
- Current as of a stated date. The certificate must show the date its information is current as of.
- Reserve study or summary attached. Lenders often ask for it, and a missing one creates questions.
- Six months of approved board minutes. Plus minutes from the most recent association meeting.
- Insurance statement included. Including who pays the deductible under the governing documents.
- CIC Board registration certification. With the filing number and expiration date.
- Your unit's violation status. Resolved items documented, open items understood.
The buyer's review and cancellation rights
Source: Code of Virginia sections 55.1-2308, 55.1-2309, 55.1-2311 and 55.1-2312 (current September 2026). "Days" means calendar days under section 55.1-2307. General information, not legal advice.
| Situation | Buyer's cancellation period | What it means for you |
|---|---|---|
| Certificate delivered before the contract is ratified | The period set in the contract, or three days from ratification if none is set | The earliest way to close the review window |
| Certificate delivered after ratification | The period set in the contract, or three days from receipt if none is set | Your contract is not fully firm until this window passes |
| Certificate, or notice that it is unavailable, never delivered | Any time before settlement | The buyer keeps an exit right until closing |
| Buyer cancels within the allowed period | Without penalty | The deposit must be returned promptly |
| Rights not used before settlement | Waived conclusively | The contract must disclose this to the buyer |
Two protections worth knowingA seller is not liable to the buyer for erroneous information the association puts in the certificate, or for the association's delay in producing it (section 55.1-2313). And the buyer is not liable for unpaid assessments greater than the amount the certificate states, which is why your account balance needs to be accurate before settlement.
Which Condo Fees and Selling Costs Should You Expect?
Condo sellers pay two kinds of costs, and it helps to keep them in separate columns. Association charges come from your condo's governance. Transaction costs come from the sale itself and look much like any other Northern Virginia home sale.
Resale certificate fees and their caps
Virginia does not let associations charge whatever they like for the resale certificate. The Common Interest Community Board publishes maximum allowable fees, indexed to inflation, and an association must be registered and current with the Board to collect them.
Source: Virginia DPOR, Common Interest Community Board, "Maximum Allowable Preparation Fees," fees effective January 12, 2023, amended July 1, 2023. The bulletin states the next mandatory CPI adjustment will occur in 2028. Payer rules from Code of Virginia section 55.1-2316.
| Item | Maximum fee | Who pays |
|---|---|---|
| Inspection of the unit (if authorized by the declaration and required to prepare the certificate) | $141.31 | Seller |
| Preparation and delivery, electronic | $176.64 total | Seller |
| Preparation and delivery, paper (up to two copies) | $211.96 | Seller |
| Optional expedite (completed within five business days, only if the preparer agrees) | $70.66 | Seller, if requested |
| Optional additional hard copy | $35.33 | Seller, if requested |
| Pre-settlement update | $70.66 | The party requesting the update |
| Additional inspection at the buyer's request | $141.31 | Buyer, if requested |
| Post-closing fee to update ownership records | $70.66 | Buyer, collected at settlement |
The statute also makes the seller responsible for the fees tied to a financial update, the short account snapshot a settlement agent requests shortly before closing. The association must provide that update within three business days of the written request.
Association charges versus the rest of your closing costs
Typical line items on a Northern Virginia condo settlement statement. Amounts and allocations depend on your contract, your governing documents and your settlement company.
| Cost | Type | How it usually works |
|---|---|---|
| Resale certificate and inspection fees | Association | Paid by the seller when ordered, within the CIC Board caps |
| Dues proration | Association | The settlement agent credits or charges the seller for the portion of the dues period before and after closing |
| Outstanding balance, late fees or fines | Association | Paid from your proceeds at settlement |
| Approved special assessment | Association | Handled as your governing documents and contract specify; negotiate it in writing rather than assuming |
| Move-out, elevator or processing fees | Association | Only if your governing documents or rules provide for them; check the schedule the association must publish |
| Listing brokerage fee | Transaction | Negotiable; a traditional listing fee is commonly 3% |
| Buyer agent compensation | Transaction | Negotiated separately since the 2024 industry settlement; not automatically part of the listing fee |
| Grantor's tax and regional recording fees | Transaction | Calculated on the sale price at recordation; your settlement agent confirms the Loudoun figures |
| Settlement and title charges | Transaction | Assigned by the contract |
| Mortgage payoff | Payoff | Principal plus interest through the payoff date, sent by the settlement company |
For the recordation side, our guide to Virginia real estate transfer taxes explains how the grantor's tax and related fees are calculated.
The listing fee is the one transaction cost you can shape before you sign anything. The calculator below compares net proceeds at a traditional 3% listing fee and at our 1.5% full-service listing fee.
Seller Savings Calculator
How much more do you keep with our 1.5% listing fee?
Select a sale price to compare both net proceeds breakdowns side by side.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$7,500
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$12,750
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$15,000
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$22,500
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$30,000
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$37,500
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$45,000
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$52,500
versus a traditional 3% listing fee, with no reduction in service or marketing.
Traditional Agent, 3%
Full-Service Listing 1.5%
Extra in your pocket
$60,000
versus a traditional 3% listing fee, with no reduction in service or marketing.
Estimates only, for illustration. Association charges such as resale certificate fees, dues prorations and special assessments are not included. Closing costs vary by contract and settlement agent. Buyer agent compensation is negotiable.
For a figure that includes your payoff, your dues proration and any association balance, use our seller net sheet and bring the resale certificate numbers with you.
How Association Finances Can Affect Your Sale
A buyer purchasing your condo is also buying into the association's balance sheet. If reserves are thin, a future special assessment is likely. If insurance is inadequate, lenders may decline the project. If the association is in litigation, both buyers and lenders will want to understand it.
None of these are yours to fix alone, but all of them are yours to anticipate. Reading the resale certificate early lets you price and prepare for what a buyer will find.
Where each issue appears and why lenders ask about it. Resale certificate item numbers refer to Code of Virginia section 55.1-2310(A). Lender standards from Fannie Mae Lender Letter LL-2026-03 (March 18, 2026) and the Fannie Mae Selling Guide.
| Issue | Where it shows up | Why buyers and lenders ask |
|---|---|---|
| Reserve funding | Reserve statement, budget and reserve study (items 9, 11, 12) | Underfunded reserves often lead to higher dues or special assessments |
| Special assessments | Approved or unpaid additional assessments (item 7) | Changes the buyer's cost and, for some loans, the review |
| Planned repairs | Approved capital expenditures (item 8) and board minutes (items 17, 18) | Large projects signal future costs |
| Master insurance and deductible | Insurance statement (item 14) | Lenders set coverage and deductible limits for the project |
| Litigation | Judgments and pending actions (item 13) | Can affect the association's finances and project eligibility |
| Deferred maintenance or code violations | Government violation notices (item 16) and minutes | Fannie Mae added critical-repair requirements for condo projects in 2023 |
The reserve threshold is rising
For conventional loans reviewed under Fannie Mae's Full Review, the project's budget must allocate a minimum share of annual assessment income to replacement reserves. Lender Letter LL-2026-03 raises that minimum from 10% to 15% for loan applications dated on or after January 4, 2027.
Share of annual budgeted assessment income allocated to replacement reserves. Source: Fannie Mae LL-2026-03, March 18, 2026. Freddie Mac announced aligned changes the same day.
If you plan to list this winter, look at your association's current budget now. A project that clears 10% but not 15% could be eligible for a buyer who applies in December and ineligible for one who applies in January, unless the lender can rely on another path the Selling Guide allows.
Insurance details lenders now check
LL-2026-03 set the maximum per-unit deductible on a master property policy at $50,000 for loans with application dates on or after July 1, 2026. When the master policy has a per-unit deductible, the buyer must carry an individual unit-owner policy that covers at least that deductible.
For sellers, the practical point is simple: have the association's current insurance certificate ready, and know whether your governing documents make owners responsible for any part of the deductible. Buyers' insurance agents will ask.
Special assessments do not stay hiddenAn approved special assessment has to appear in the resale certificate, along with any unpaid balance. Decide early, with your agent and settlement company, whether you will pay it in full at closing, credit the buyer, or price around it. Surprises at this stage are what end condo contracts.
How Buyer Financing Works for a Condo Purchase
Every financed condo purchase has two approvals. The first is the familiar one: the lender qualifies the buyer on income, assets and credit. The second is the project review: the lender, or the loan program, decides whether your condominium project is an acceptable risk.
A buyer's preapproval letter covers the first approval only. It says nothing about the second, which is why a strong buyer can still hit a wall with the wrong building.
Conventional loans after August 3, 2026
Fannie Mae retired its Limited Review process in LL-2026-03, effective for all loan applications dated on or after August 3, 2026. Established projects that used to qualify for the lighter review must now go through a Full Review, or qualify for a Waiver of Project Review.
The waiver now covers new and established projects with ten or fewer units; for projects of five to ten units, the project cannot be part of a master association or larger development. Most Ashburn condo buildings are larger than that, so a Full Review is the path to expect.
What a Full Review looks atThe lender examines the project's budget and reserves, insurance, delinquencies, litigation, special assessments and physical condition, and certifies the project in Fannie Mae's Condo Project Manager tool. LL-2026-03 also retired the 50% investor concentration limit for established projects under Full Review. Freddie Mac announced aligned changes, and individual lenders can still apply stricter rules of their own.
FHA and VA loans
FHA insures condo loans in FHA-approved projects. A unit in a project that is not FHA-approved may still be eligible through a Single-Unit Approval, according to HUD, if the project is complete, has at least five units and is not a manufactured home project, among other requirements.
Single-Unit Approvals are limited: FHA-insured loans generally cannot exceed 10% of units in a project with ten or more units, or two units in smaller projects. VA works differently. Under the VA Lenders Handbook, Chapter 16, a condominium must be approved by VA before any unit in it is eligible for a VA-guaranteed loan.
Summary of how each financing path treats the condo project. Sources: Fannie Mae LL-2026-03 (March 18, 2026); HUD FHA Condominiums page and Handbook 4000.1; VA Lenders Handbook (VA Pamphlet 26-7), Chapter 16. Program rules change; the buyer's lender confirms eligibility for each loan.
| Financing path | Project requirement | What to check early |
|---|---|---|
| Conventional (Fannie Mae or Freddie Mac) | Full Review or Waiver of Project Review; Limited Review retired for applications on or after Aug 3, 2026 | Reserves, delinquencies, insurance, litigation, critical repairs |
| FHA | FHA-approved project, or a Single-Unit Approval where eligible | Whether the project is on the FHA approved list and its FHA concentration |
| VA | VA project approval required before any unit is eligible | Whether the project appears on VA's approved condominium list |
| Non-warrantable or portfolio loan | Set by the individual lender | Down payment and rate terms, which are often less favorable to the buyer |
| Cash | None from a lender | Proof of funds; the buyer still receives the resale certificate |
Warrantable versus non-warrantable condos
A warrantable condo is one whose project meets Fannie Mae and Freddie Mac standards, so lenders can sell those loans. A non-warrantable project fails at least one standard, which pushes buyers toward portfolio loans or cash.
Being non-warrantable does not make a condo unsellable. It narrows the buyer pool and usually affects price and timing, which is exactly why you want to know your building's status before you set a list price.
What Can Delay or Derail Buyer Financing?
Condo financing rarely fails because of the buyer. It fails because a document is missing, a questionnaire goes unanswered, or the project review turns up something nobody checked. Most of these problems can be spotted before you list.
Common failure points in condo financing and how sellers can reduce the risk. General guidance; individual lenders set their own documentation requirements.
| Problem | How it shows up | What you can do |
|---|---|---|
| Slow or incomplete condo questionnaire | The buyer's lender cannot finish the project review | Ask the management company about its lender questionnaire process and turnaround before listing |
| Insurance does not meet program limits | Deductible or coverage fails the lender's review | Get the current master policy certificate and share it early |
| Low reserves or high delinquencies | Project fails Full Review standards | Review the budget and ask the board about delinquency levels |
| Critical repairs or safety issues | Project becomes ineligible until repairs are completed | Read recent minutes and any engineering or inspection reports |
| Pending litigation | Lender requests details or declines the project | Obtain the association's written summary of the case |
| Appraisal gap | Appraisal comes in below the contract price | Price from condo comparables in your own project and give the appraiser your comparable package |
A preapproval is not a project approvalWhen comparing offers, ask whether the buyer's lender has looked at your project yet. A lender who has already started the project review, or who confirms the building is on the FHA or VA list for those loans, is giving you far more certainty than a preapproval letter alone.
If your building has financing questions, or your timeline cannot absorb a failed project review, it is worth seeing a cash option next to a market listing before you decide. We will lay both out plainly, with no pressure either way.
How to Prepare and Market Your Ashburn Condo
Condo buyers compare units that often share a floor plan, a lobby and a parking lot. When the building is the same, presentation and clear information decide which unit gets the offer.
That makes preparation less about renovation and more about removing doubt: fixing small things, photographing the space well, and answering the association questions before a buyer has to ask.
Presentation priorities
Before photography day
- Small repairs first. Dripping faucets, loose hardware, worn caulk, scuffed trim and burned-out bulbs read as neglect in a small space.
- Neutral, bright rooms. Fresh paint and added lighting help condos, where some rooms may have only one exterior wall.
- Clear the balcony or patio. Two chairs and a clean surface show usable outdoor space better than stored items.
- Empty the storage unit. If a storage space conveys, a cleared one photographs as real square footage.
- Professional photography and a floor plan. A dimensioned floor plan helps buyers compare your layout with others in the building.
Features worth verifying and highlighting
Only market what you can document. Parking that is assigned by the association is different from a deeded space, and a storage unit that is a limited common element is different from one you rent. Your declaration and the resale certificate tell you which is which.
The same goes for location. If your community is near the Ashburn station on Metro's Silver Line, state the verified walking distance from a mapping tool rather than an estimated travel time, and let buyers judge the commute for themselves.
Listing details that condo buyers look for and how to present them accurately.
| Feature | How to verify it | How to present it |
|---|---|---|
| Parking | Declaration, parking assignment records, garage documents | Number of spaces, assigned or deeded, covered or open |
| Storage | Declaration or assignment records | Location and size, and whether it conveys |
| Accessibility features | Building specifications and association information | Elevator access, step-free entry and door widths as factual features |
| Outdoor space | Plats and plans, limited common element designation | Balcony or patio size and orientation |
| Metro access | Mapping tool distance from your building entrance | Distance to the station, without promised commute times |
| Monthly dues | Resale certificate and current budget | Amount plus an itemized list of what the fee covers |
Explain the dues, do not just list them
A monthly fee shown as a bare number invites a buyer to compare it with a townhouse fee and walk away. The same fee listed with what it covers, such as exterior maintenance, roof and common-area reserves, water, trash, snow removal, insurance on the structure or amenities, tells a much more complete story.
Pull those inclusions from your budget and governing documents, not from memory. If the fee does not cover something buyers commonly assume, say so; accuracy protects you later in the transaction.
A note on the wider DMV marketAshburn condo buyers rarely shop Ashburn alone. Many are comparing payments across eastern Loudoun, western Fairfax and sometimes Maryland or DC before they choose. Our team works across the region as DMV real estate specialists, which is why pricing conversations start with where your likely buyer is actually shopping.
Professional photography, floor plans, full MLS exposure, resale certificate tracking and negotiation are included in our full-service listing at 1.5%. Compared with a traditional 3% listing fee, the difference stays with you at settlement.
How to Compare Offers on Your Condo
On a condo, the highest price is not always the strongest offer. The loan type, the lender's progress on your project review, the contingencies and the concessions all change how likely the contract is to close and what you actually net.
The example below uses invented round numbers purely to show the comparison. It does not describe any real transaction.
Hypothetical example for illustration only. Figures are not from any real sale.
| Factor | Offer A | Offer B | Offer C |
|---|---|---|---|
| Price | $455,000 | $450,000 | $440,000 |
| Financing | FHA | Conventional | Cash |
| Project status for that loan | Project not yet confirmed on the FHA list | Lender has started the Full Review | Not applicable |
| Seller concession requested | $9,000 | None | None |
| Contingencies | Financing, appraisal, inspection | Financing, appraisal | Inspection only |
| Price after concession | $446,000 | $450,000 | $440,000 |
| Closing risk to weigh | Highest, because project eligibility is unknown | Moderate, and review is underway | Lowest financing risk |
In that example, the highest headline price nets the least after the concession and carries the most uncertainty. Always compare offers on estimated net proceeds and likelihood of closing, then run the numbers through your net proceeds estimate before you respond.
Questions to ask about every financed offer
Ask the buyer's agent or lender
- Has the lender reviewed our project? Or at least confirmed it can lend in it under the chosen program?
- Which review applies? Full Review, waiver, FHA project approval, Single-Unit Approval or VA approval.
- What will the lender need from the association? And has the questionnaire been requested?
- What cancellation period does the contract set for the resale certificate review, if any?
- Is the requested closing date realistic given the association's turnaround times?
What Happens Between Contract and Closing?
Once the contract is ratified, several parties work in parallel. Knowing who owns each task keeps your settlement date from slipping because everyone assumed someone else had it.
Typical division of responsibilities in a Virginia condo sale. Your contract and your settlement company's process control the specifics.
| Task | Responsible party | Seller's role |
|---|---|---|
| Deliver the resale certificate to the buyer | Seller or listing agent | Confirm delivery date in writing |
| Home inspection | Buyer and inspector | Provide access to the unit, storage and utility areas |
| Appraisal | Buyer's lender and appraiser | Provide access; your agent supplies a condo comparable package |
| Project review and lender questionnaire | Buyer's lender and the association or management company | Help connect the lender with management if responses stall |
| Financial update and account check | Settlement company and association | Pay any balance or fee so the account is current |
| Updated resale certificate, if needed | Requested by seller or buyer | Request it if settlement moves past 30 days from issue |
| Mortgage payoff and prorations | Settlement company | Provide lender details and review the settlement statement |
| Move-out | Seller | Reserve elevators or loading areas under association rules; return keys and fobs |
Ratification and certificate delivery
The contract becomes firm, and the buyer's resale certificate review period begins as described in the contract or the statute.
Inspection and review window
The buyer inspects the unit and reads the association documents. Questions about reserves, rules or assessments usually surface here.
Appraisal and project review
The lender orders the appraisal and completes the project review. This is where missing association information causes most delays.
Final account check
The settlement agent requests the financial update; the association must respond within three business days.
Settlement and move-out
Funds disburse, the association's records are updated, and you hand over keys, fobs and remotes.
What We Are Seeing Locally
Market reports describe a county. This section describes our own transaction record in the Ashburn area, which is a much smaller and narrower thing. It shows where our experience comes from; it does not measure the market.
The Jamil Brothers Record
Every Closing, One Honest List
Community split: 113 Ashburn, 13 Broadlands, 13 Brambleton. Six closings were both sides of the same transaction, and 27 have closed since the start of 2024. Eleven of the 139 were condo or flat units.
Savings method: 1.5% of the close price on each closing where we represented the seller, which is the spread between a traditional 3% listing fee and our 1.5% full-service listing fee. Illustrative only. It is not a quote, not an average outcome and not a prediction of future savings. Team data is a small sample of one team's business, not a market report.
The Jamil Brothers Record · Ashburn · Broadlands
15 Homes We Closed in Ashburn in 2025 and 2026
These are 15 closings from our 2025 and 2026 record in Ashburn, including the Broadlands community in the 20148 ZIP code. Switch years with the tabs. Close prices are public record, and client names are never shown.
| Address | City | Close price | Structure type |
|---|---|---|---|
| 42529 Carnforth Ct | Broadlands, VA | $2,940,511 | Single-family detached |
| 22970 Weybridge Sq | Broadlands, VA | $935,000 | Townhouse (end unit) |
| 23012 Weybridge Sq | Broadlands, VA | $910,000 | Townhouse (interior) |
| 23430 Madison Heights Ter | Ashburn, VA | $707,000 | Townhouse (interior) |
| 43279 Rush Run Ter | Ashburn, VA | $700,000 | Townhouse (interior) |
| 21622 Monmouth Ter | Ashburn, VA | $690,000 | Townhouse (end unit) |
| 20696 Erskine Ter | Ashburn, VA | $576,000 | Townhouse (end unit) |
| Address | City | Close price | Structure type |
|---|---|---|---|
| 19679 Peach Flower Ter | Ashburn, VA | $931,434 | Townhouse (interior) |
| 20052 Old Line Ter | Ashburn, VA | $895,000 | Townhouse (end unit) |
| 42892 Bold Forbes Ct | Ashburn, VA | $850,000 | Single-family detached |
| 44506 Lowestoft Sq | Ashburn, VA | $810,000 | Townhouse (end unit) |
| 21170 Wildflower Sq | Ashburn, VA | $665,000 | Townhouse (interior) |
| 43131 Waldstone Ter | Ashburn, VA | $635,000 | Townhouse (interior) |
| 43700 Hamilton Chapel Ter | Ashburn, VA | $615,000 | Townhouse (interior) |
| 22262 Meadfoot Ter | Ashburn, VA | $525,000 | Townhouse (interior) |
What These 15 Closings Tell an Ashburn Condo Seller
Fifteen sales from one team are not a market report. They are a real, checkable slice of Ashburn activity, and read correctly they explain several of the pricing rules in this guide.
How to use this record if you are selling a condo
- Do not borrow these prices as condo comparables. The lowest townhouse here closed at $525,000, close to the $509,303 Loudoun condo average for 2025 activity in the county's assessment data. Overlapping prices are exactly why appraisers still separate the two property types.
- Know who you are really competing with. A buyer shopping $500,000 to $600,000 in Ashburn may tour your condo and an older interior townhouse in the same week. Your listing has to explain what the dues cover, because the townhouse down the street usually carries a lower fee and no project review.
- Treat the first two weeks as the whole launch. Our fastest listings sold in under a week, and the slowest was the one priced most aggressively. Condos sell to a smaller, payment-focused buyer pool, so that lesson applies with even more force.
- Expect a wide spread, not an average. These 15 homes run from $525,000 to $2,940,511. Any single Ashburn average blends homes like these together, which is why your price should come from your own building's sales.
What changed for Ashburn condo sellers this year
The most important local shift is regulatory, not price-driven. For most Ashburn condo buildings, a conventional buyer who applied on or after August 3, 2026 now depends on a Full Review of the project rather than the lighter Limited Review that established projects could previously use.
In practice, that moves the association's budget, reserves, insurance and delinquency figures from background paperwork to front-line pricing information. That is why we recommend requesting the budget and reserve study summary at the listing stage, alongside the resale certificate.
What our numbers can and cannot tell youEleven condo closings in one area are enough to shape how we read association documents and lender questions. They are nowhere near enough to set a median price or a days-on-market figure. For those, we rely on Bright MLS reporting and Loudoun County's published assessment data, cited in this guide with their data periods.
Ashburn Condo Seller Checklist
Use this as a one-page summary of the guide. Each item maps to a section above.
Pricing
- Pull condo sales from your own project first, then similar projects, and leave townhouses out of the comparable set.
- Adjust for floor, parking, storage, outdoor space, renovations and dues.
Documents and association balances
- Request the resale certificate in writing when you decide to list, from every association that governs your unit.
- Read it before any buyer does, including reserves, special assessments, minutes and any violation notice.
- Gather your own records: approvals, permits, warranties, parking and storage documents, and the Virginia disclosure.
- Bring your account current and confirm the balance matches the certificate.
Financing questions
- Check the project's FHA and VA status and ask management about the conventional lender questionnaire.
- Note the reserve allocation in the current budget, especially if you may sell after January 4, 2027.
- Have the master insurance certificate ready for lenders and buyers' insurance agents.
Showing access and closing preparation
- Confirm showing access rules for lobby entry, fobs and parking for visitors.
- Compare offers on net proceeds and likelihood of closing, not headline price.
- Track the buyer's review window and request an updated certificate if settlement moves.
- Reserve move-out logistics under association rules and collect keys, fobs and remotes.
Frequently Asked Questions
Is selling a condo different from selling a townhouse in Ashburn?
Yes. When selling a condo in Ashburn, the buyer's lender reviews the entire condominium project as well as your unit, while a fee-simple townhouse generally does not go through a full project review. Condo buyers also look closely at the association's reserves, insurance, special assessments and monthly dues, because those belong to the whole building. Both property types require a resale certificate under Virginia's Resale Disclosure Act, but a condo sale usually involves more association documents and more financing questions.
What association documents do I need before selling?
The key document is the resale certificate, which Virginia requires the seller to obtain from the association and provide to the buyer under Code of Virginia section 55.1-2309. It includes the governing documents and rules, assessment amounts, any special assessment, the budget, reserves and reserve study, insurance information, pending litigation, recent board and association minutes, and any violation notices on your unit. You should also gather your own renovation approvals, permits, warranties, parking and storage records, and the Virginia residential property disclosure statement.
When should I order my condo resale certificate?
Order it in writing as soon as you decide to list. The association has 14 days after a written request to deliver it, and if nothing arrives within that period the certificate is deemed unavailable, which changes the buyer's rights. Ordering at listing also lets you read the certificate before any buyer does, so you can resolve a violation notice or prepare for questions about reserves or assessments. If settlement is later more than 30 days after the certificate was issued, an updated certificate can be requested and must be delivered within 10 days.
Who pays the resale package fees?
Under Code of Virginia section 55.1-2316, the seller pays all fees for preparing and delivering the resale certificate, including any required inspection of the unit, and the seller is also responsible for the financial update fee. The party who requests an updated certificate pays for that update, and the buyer pays the post-closing fee that updates the association's ownership records. The Common Interest Community Board caps these fees; as of the fee schedule effective January 12, 2023 and amended July 1, 2023, electronic preparation and delivery is capped at $176.64 and a required inspection at $141.31.
Can I sell my condo with an outstanding special assessment?
Yes. An outstanding special assessment does not prevent a sale, but it must appear in the resale certificate along with any unpaid amount, so the buyer will see it. How it is handled at settlement depends on your governing documents and on what you negotiate, such as paying the balance from your proceeds, offering the buyer a credit, or reflecting it in the price. Decide on your approach before you list and put it in writing in the contract, because an unexpected assessment discovered during the buyer's review period is a common reason condo contracts are cancelled.
How do monthly condo fees affect buyer affordability?
Lenders count monthly condo dues in the buyer's debt-to-income ratio, so higher dues reduce the loan amount a buyer can qualify for at the same income. As an illustration only, at a 7% fixed rate on a 30-year loan, each $100 of monthly dues uses about the same payment capacity as roughly $15,000 of loan principal. That is why units with higher dues often need to be priced accordingly, and why your listing should itemize what the fee covers, such as exterior maintenance, reserves, water, trash or amenities.
What happens if my condo project does not qualify for the buyer's loan?
If the project fails the review for the buyer's loan program, that buyer cannot use that financing for your unit, and a financing contingency usually allows them to cancel. The buyer may be able to switch to a different program, a portfolio or non-warrantable loan with different terms, or cash. For future buyers, you can ask the association what caused the failure, since some issues such as missing insurance documentation can be corrected, while others such as low reserves or pending litigation take longer. Checking eligibility before you list is the best protection.
Can a buyer use FHA or VA financing to purchase my condo?
Possibly, depending on your project's status. FHA insures condo loans in FHA-approved projects, and HUD also allows a Single-Unit Approval for some units in projects that are not FHA-approved, if the project is complete, has at least five units and meets other requirements, with limits on how many FHA loans a project can hold. VA requires the condominium project itself to be approved before any unit is eligible for a VA-guaranteed loan. Ask your agent to check both lists before you compare offers.
How long can a buyer cancel after receiving the resale certificate?
Under Code of Virginia section 55.1-2312, the buyer can cancel within the period set in the ratified contract. If the contract sets no period, the buyer has three days from ratification when the certificate was delivered before ratification, or three days from receipt when it was delivered after. If the certificate, or a notice that it is unavailable, is never delivered, the buyer may cancel at any time before settlement. Cancellation within the allowed period is without penalty, and the deposit must be returned promptly.
Do Fannie Mae's 2026 condo changes affect my Ashburn sale?
They likely do if your buyer uses a conventional loan. Fannie Mae Lender Letter LL-2026-03 retired the Limited Review for loan applications dated on or after August 3, 2026, so most established condo projects now need a Full Review unless they qualify for a Waiver of Project Review for projects of ten or fewer units. The same letter raises the minimum reserve allocation from 10% to 15% of budgeted assessment income for applications dated on or after January 4, 2027, and caps the master policy per-unit deductible at $50,000 for applications dated on or after July 1, 2026.
Who is the best realtor in Ashburn, VA?
In our opinion, The Jamil Brothers Realty Group is the best choice for Ashburn condo sellers, and we base that view on a verifiable local record rather than a slogan. The team has 139 unique closings across Ashburn, Broadlands and Brambleton, including 11 condo or flat units, and operates under Samson Properties with licenses in Virginia, Maryland, Washington DC and West Virginia. Whoever you interview, ask for recent condo sales in your own community and for how they handle resale certificates and lender project reviews, because those two skills matter most in a condo sale.
Glossary
Plan Your Ashburn Condo Sale
Selling a condo in Ashburn rewards the seller who starts with paperwork rather than paint. Order the resale certificate, read the budget and reserves, and confirm how your project stands with conventional, FHA and VA lenders before you choose a list price.
Then price from condo sales in your own project, explain your dues in plain terms, and compare offers on net proceeds and certainty of closing. That sequence prevents most of the problems that stall condo contracts late in the process.
We review recent sales in your project, flag the association documents to order first, and estimate what reaches your account at settlement after association charges and closing costs. Free and without obligation.
Not ready for a valuation yet? You are welcome to send us a question about your resale certificate or building, or call (703) 782-4830. We will point you to the right documents, whether or not you list with us.
Explore More
Sell My Home Home Valuation Seller Net Sheet Cash Offers Flexible Commissions 1.5% Commission Real Estate NoVA Northern Virginia Loudoun County About Us Meet Our Team ContactRelated Ashburn Guides
Ashburn Communities and Nearby Areas
Condo buyers in Ashburn often compare units in nearby Loudoun communities. These are the area guides we maintain, starting inside Ashburn.
Inside Ashburn
Nearby Loudoun Areas
Data sources and dates: Code of Virginia, Title 55.1, Chapter 23.1 (Resale Disclosure Act), as published by the Virginia Legislative Information System, current September 2026; Virginia DPOR Common Interest Community Board, Maximum Allowable Preparation Fees (effective January 12, 2023, amended July 1, 2023); Fannie Mae Lender Letter LL-2026-03 (March 18, 2026); HUD FHA Condominiums guidance and Handbook 4000.1; VA Lenders Handbook (VA Pamphlet 26-7), Chapter 16; Loudoun County 2026 Real Property Assessment presentation (February 3, 2026), twelve-month averages from Bright MLS reflecting 2025 activity. Team transaction figures are The Jamil Brothers Realty Group's own closed sales record and are showcase information only, not a market report. Rules and market conditions change; verify current requirements before making a decision. The Jamil Brothers Realty Group is licensed in Virginia, Maryland, Washington DC and West Virginia and operates under Samson Properties.
Categories
- All Blogs (1243)
- Buyer Guide (8)
- Buying a home (2)
- Buying Strategies (31)
- festivals (1)
- General Blog (67)
- Market Intelligence (29)
- Market Updates (8)
- Notable Properties For Sale (32)
- Real Estate Tips, News, and More (395)
- Seller Guide (2)
- Seller Guides (60)
- Selling Your Home (527)
- Top Realtors in Northern Virginia (58)
Recent Posts



Let's Connect