How Mortgage Rates Affect Selling Your Home in Ashburn, VA (2026 Guide)
Quick Answer: How Do Mortgage Rates Affect Selling Your Home in Ashburn?
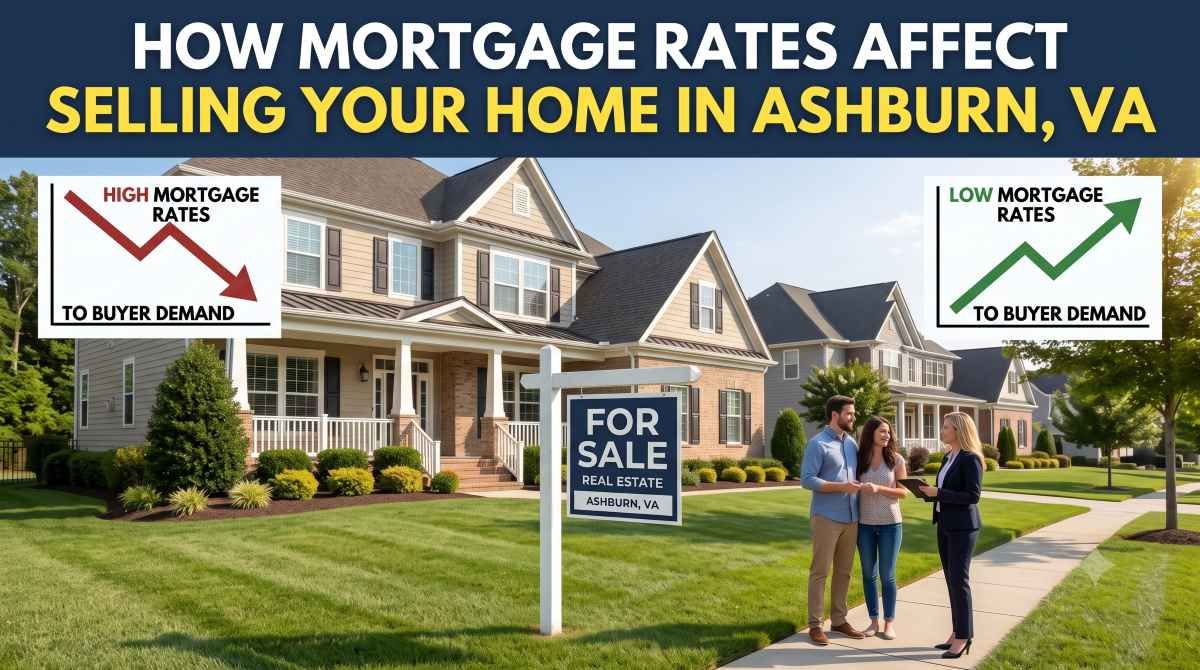
Mortgage rates primarily affect a home sale in Ashburn, VA by changing buyer affordability. When rates rise, buyers generally pay more each month to borrow the same amount. This can reduce their budgets, limit the number of qualified buyers, and increase pressure on sellers to price accurately.
Higher rates do not automatically cause home prices to fall. Local inventory, property condition, neighborhood demand, and competing listings also influence what buyers will pay.
For context, Freddie Mac reported a 7.40% average 30 year fixed mortgage rate on October 15, 2026, compared with 6.27% a year earlier. NVAR's September 2026 report for Loudoun County, based on Bright MLS data, recorded a median sold price of $758,500 and 2.41 months of supply, even as closed sales declined 17.8% year over year.
Mortgage rates are only one part of your selling decision. Local home values, competing listings, your equity, and your plans after the sale also influence the outcome. For homeowners considering a sale, the practical approach is to evaluate current comparable sales, estimate selling costs, and understand the competition for their property type.
The Jamil Brothers Realty Group offers full service home selling with listings from 1.5%, with premium marketing and partner-led negotiation. This lets Ashburn homeowners compare listing costs alongside the marketing and selling services included in their agreed package.
Free, No Obligation
Selling in Ashburn? Get a Rate-Smart Plan
Tell us about your home and we will send a pricing and timing plan built for today's rates.
Prefer to talk? Call (703) 782-4830 or use our contact page.
Key Takeaways
- Rates work on the buyer side. Higher mortgage rates can reduce buyer purchasing power and shift negotiations toward credits and buydowns.
- Rates are higher than a year ago. Freddie Mac reported a 7.40% average 30 year fixed rate on October 15, 2026, compared with 6.27% one year earlier.
- Loudoun values held while sales slowed. NVAR reported a $758,500 Loudoun County median sold price in September 2026 (up 0.8%), while closed sales fell 17.8% year over year. County figures cannot determine the value of an individual Ashburn home.
- Waiting is not a guaranteed win. Waiting for lower rates is not guaranteed to produce a better sale price or a better overall outcome.
- Listing fees are a cost you can compare. On a $750,000 sale, a 1.5% listing fee is $11,250 less than a 3% listing fee, assuming the same sale price.
- Other costs are separate. Buyer agent compensation, if agreed, and other selling expenses are separate from the listing fee and are negotiable.
In This Guide
- How Do Mortgage Rates Affect Your Ashburn Home Sale?
- What Do 2026 Mortgage Rates Mean for Ashburn Home Sellers?
- What Are the Latest Loudoun County Housing Market Statistics?
- What We Are Seeing Locally in Ashburn and Loudoun County
- How Does the Rate Lock In Effect Apply When You Are Both a Seller and a Buyer?
- Should You Sell Now or Wait for Lower Mortgage Rates?
- How Do You Sell an Ashburn Home When Mortgage Rates Are High?
- How Can You Protect Your Net Proceeds When Rates Are High?
- When Does a Cash Offer Make Sense in a High Rate Market?
- Glossary: Mortgage Rates and Selling Terms
- What Should Ashburn Sellers Take Away?
- Frequently Asked Questions
How Do Mortgage Rates Affect Your Ashburn Home Sale?
Mortgage rates do not directly determine your home's sale price. Instead, they affect the number of buyers who can afford it and the terms they may request. Four factors deserve particular attention when you prepare to sell.
1. Do Higher Rates Reduce Buyer Purchasing Power?
Yes. Most buyers make purchasing decisions around a monthly housing payment rather than the asking price alone. When mortgage rates increase, the same monthly budget supports a smaller loan.
A buyer who qualifies for a particular purchase price at one interest rate may need to lower their budget if the rate rises. Other buyers may increase their down payment, choose a smaller property, or negotiate for seller concessions.
This matters when your home competes with similar townhomes or single family properties in Ashburn.
The practical response is not necessarily to lower your asking price immediately. Start by reviewing recent comparable sales, identifying your likely buyers, and comparing your property with current listings.
2. Can a Smaller Buyer Pool Increase Time on Market?
Higher mortgage payments can make buyers more selective. If your home is overpriced, poorly presented, or competing with better positioned listings, it may receive fewer showings and take longer to attract an acceptable offer.
A longer selling period does not automatically mean your home has lost value. It may indicate that the asking price, marketing, condition, or terms need to be reconsidered.
Accurate pricing and professional presentation become especially important when buyers have more choices. Your property needs to offer a clear reason for buyers to consider it alongside competing homes.
3. Will Buyers Negotiate More Aggressively?
Often, yes. When affordability is tight, buyers may request repairs, closing cost assistance, or a mortgage rate buydown. These requests can affect your net proceeds, even when the agreed sale price initially looks attractive.
Consider two hypothetical offers. One buyer offers a higher price but requests a substantial credit. Another offers a slightly lower price with fewer concessions and terms that better fit your plans. The better offer depends on the complete transaction, not just the headline price.
Compare financing conditions, contingencies, inspection requests, closing dates, requested credits, and estimated proceeds before deciding how to respond.
4. Do Mortgage Rates Determine Local Prices on Their Own?
No. Housing prices reflect the balance between buyer demand and available properties. Higher rates can reduce demand, but they can also discourage homeowners with low existing mortgage rates from selling.
That can limit the number of competing listings. However, the effect varies by neighborhood, property type, price range, and economic conditions.
It would be misleading to conclude that Ashburn prices will always remain firm simply because inventory is limited. Review recent comparable sales and competing listings for your specific property before choosing an asking price.
Which Parts of Your Sale Are Most Affected by Mortgage Rates?
| Factor | Potential effect |
|---|---|
| Buyer purchasing power | Higher rates increase borrowing costs. |
| Number of qualified buyers | Fewer buyers may qualify at a given price. |
| Time on market | May increase when demand weakens or pricing misses the market. |
| Negotiation | Buyers may request credits, repairs, or buydowns. |
| Final sale price | Depends on rates, inventory, condition, pricing, and demand. |
| Listing fee | Determined by your listing agreement, not mortgage rates. |
You cannot control national mortgage rates, but you can compare listing services and fees before signing an agreement.
What Do 2026 Mortgage Rates Mean for Ashburn Home Sellers?
Rates are noticeably higher than a year ago. Freddie Mac's Primary Mortgage Market Survey reported the following national weekly averages.
| Rate observation | 30 year fixed | 15 year fixed |
|---|---|---|
| October 15, 2026 | 7.40% | 6.71% |
| One year earlier | 6.27% | 5.52% |
Source: Freddie Mac, Primary Mortgage Market Survey, week of October 15, 2026. National averages for conventional, conforming purchase loans.
These are national survey averages, not guaranteed rates for individual borrowers. Actual mortgage offers vary according to credit, down payment, loan type, points, and other factors.
How Much Can a Higher Rate Change a Buyer's Payment?
Consider a hypothetical buyer borrowing $600,000 through a 30 year fixed mortgage.
| Interest rate | Estimated monthly principal and interest |
|---|---|
| 6.27% | $3,702 |
| 7.40% | $4,154 |
| Monthly difference | $452 |
These figures are approximate principal and interest payments only. They exclude property taxes, insurance, mortgage insurance, HOA dues, and other housing expenses.
The difference is approximately $5,426 a year. That can be a meaningful change for a household managing a fixed budget.
This example explains why some buyers may become more sensitive to asking prices and seller concessions when rates rise. It does not mean every buyer will reduce their budget by the same amount. For sellers, the goal is to understand the affordability range of likely buyers and price the property accordingly.
How Do Rising and Falling Mortgage Rates Affect Your Sale?
| Factor | When rates rise | When rates fall |
|---|---|---|
| Buyer budgets | Monthly payments rise for the same loan. | Borrowing may become more affordable. |
| Buyer demand | Some buyers may delay or reduce budgets. | Some buyers may return to the market. |
| Competing listings | Some owners may postpone selling. | More previously inactive owners may list. |
| Negotiation | Buyers may request more concessions. | Competition and offer terms may change. |
| Your next purchase | Financing may cost more. | Financing may become less expensive, depending on the offer. |
Falling rates can benefit buyers, but the resulting market depends on how demand and supply change together. No one can guarantee that a future rate reduction will create better conditions for every seller.
What Are the Latest Loudoun County Housing Market Statistics?
Loudoun County had more listings and fewer sales in September 2026, while the median sold price edged up. NVAR's September 2026 report, published October 16, 2026 and based on Bright MLS data, provides this countywide snapshot for all property types.
| Market indicator | September 2026 | Year over year |
|---|---|---|
| Median sold price | $758,500 | +0.8% |
| Closed sales | 338 | −17.8% |
| Total sales volume | $288,344,660 | −18.6% |
| Average days on market | 31 days | +6.9% |
| Active listings | 1,031 | +34.1% |
| Months of supply | 2.41 | +37.7% |
Source: Northern Virginia Association of Realtors, Market Statistics: September 2026, Loudoun County, all property types, Bright MLS data.
These figures describe Loudoun County as a whole. They are not Ashburn only statistics and should not be treated as a valuation for an individual home.
What Do These Numbers Mean for Sellers?
- ✓More listings mean more competition. With 1,031 active listings in September 2026, Loudoun buyers had more properties to compare than a year earlier. Price, condition, presentation, and marketing therefore matter.
- ✓Fewer sales do not automatically mean lower values. The county median rose 0.8% year over year, but a median reflects the mix of properties sold during the month. It does not establish that every property appreciated.
- ✓Marketing periods may vary. Loudoun's average days on market was 31 days in September 2026. Your property may sell faster or take longer depending on its price, location, condition, and competition.
- ✓Inventory needs context. Months of supply shows the balance between available properties and the current sales pace. At 2.41 months, Loudoun had more supply than a year earlier, but the figure alone cannot predict the outcome for an individual listing.
The limits of countywide averages
A single county median blends detached homes, townhomes, and condos from every part of Loudoun, from Ashburn and Sterling to rural western towns, and it reflects one month of closings. Your home's value depends on its neighborhood, ZIP code, property type, condition, and price band.
For a wider view of conditions across the region, see our Northern Virginia real estate services and Loudoun County real estate guides.
What We Are Seeing Locally in Ashburn and Loudoun County
Ashburn is the city where our team has closed the most transactions. The Jamil Brothers' MLS records show 113 unique Ashburn closings.
113
Unique Ashburn closings in our team's MLS records
$758,500
Loudoun median sold price, Sept 2026 (NVAR)
31 days
Loudoun average days on market, Sept 2026 (NVAR)
2.41
Loudoun months of supply, Sept 2026 (NVAR)
This is our team's transaction history, not a count of every home sold in Ashburn. Our experience provides local context, while broader market conclusions should be based on published MLS and association data.
What Does One Ashburn Listing Example Show?
| Detail | Ashburn townhouse, Loudoun County |
|---|---|
| List price | $755,000 |
| Sold price | $785,000 |
| Days on market | 5 |
| Offers received | 5 |
| Strategy on record | Strategic pricing above nearby comparable sales, backed by cinematic video marketing |
This single sale is an example from our listing records, not a representative sample of the Ashburn market. Results depend on the property, its price band, its condition, and conditions at the time of sale.
Why Does Property Type Matter?
Detached homes, townhomes, and condos do not necessarily compete for the same buyers. Their prices, monthly ownership costs, available inventory, and features differ.
A townhome may compete with other attached properties that offer similar layouts and amenities. A detached home may attract buyers who need a larger lot, additional space, or more privacy. That is why a countywide median cannot determine what a particular Ashburn home is worth.
Why Does the Exact Neighborhood Matter?
Ashburn includes communities with different housing styles, amenities, price ranges, and buyer expectations.
A property in Ashburn Village may compete with different homes than one in Broadlands, Brambleton, One Loudoun, or Belmont Country Club.
The Jamil Brothers evaluate comparable properties and current competition within the relevant area rather than relying exclusively on county averages.
Why Does Accurate Pricing Matter in a Changing Market?
When buyers have more choices and higher financing costs, a property needs a clear value proposition.
Pricing too high can reduce early interest. Pricing too low without a deliberate strategy can leave money on the table. Both are among the common mistakes Ashburn sellers make.
The right asking price should reflect comparable sales, current listings, property condition, and your selling goals.
How Does the Rate Lock In Effect Apply When You Are Both a Seller and a Buyer?
Many homeowners are not selling simply to access their equity. They may be moving to a larger home, downsizing, relocating, or purchasing a property elsewhere in Northern Virginia. If you plan to buy again, your next mortgage matters just as much as the loan your current buyer will use.
How Does the Rate Lock In Effect Work?
Homeowners who secured low mortgage rates in previous years may hesitate to sell because buying another property could mean taking on a higher rate.
When many owners delay listing, fewer properties may come onto the market. That can limit buyer choices, although the actual effect depends on current supply and demand.
For homeowners who need to move, avoiding a higher mortgage rate is not the only financial consideration.
How Can Your Existing Equity Affect Your Next Purchase?
If your home has accumulated equity, selling it may allow you to make a larger down payment on your next property. A larger down payment can reduce the amount you need to borrow.
However, the outcome depends on your sale price, mortgage payoff, selling costs, the cost of the next home, and the financing available to you.
Waiting may also bring additional mortgage payments, taxes, maintenance costs, or changes in the price of the property you want to buy.
Should You Sell and Buy at the Same Time?
The decision requires planning around your sale proceeds, financing, and moving dates.
Depending on your circumstances, you might explore a contingent offer, a rent back arrangement, or bridge financing with an appropriate lender. Each option has eligibility requirements, costs, and risks.
Plan the sale and purchase sequence before committing to either transaction. A selling and buying strategy session can help you map both sides.
Should You Sell Your Ashburn Home Now or Wait for Lower Mortgage Rates?
Waiting for mortgage rates to fall may seem appealing, but it is not a guaranteed way to improve your financial outcome.
If rates fall, some buyers may regain purchasing power. At the same time, homeowners who postponed selling may decide to list their properties, increasing competition.
If rates remain high, you may face ongoing ownership costs while waiting for a change that may take longer than expected.
Selling Now Versus Waiting
| ✓ Selling now | ○ Waiting for lower rates |
|---|---|
| You can make decisions using current comparable sales and listings. | Future rates and prices are uncertain. |
| You can move according to your personal timeline. | You continue paying ownership costs while waiting. |
| Your next purchase can be planned using current financing estimates. | Your next purchase price and financing costs may change. |
| You can compare current offers and selling costs. | More sellers may enter the market if conditions change. |
Neither option is automatically better. The right choice depends on your equity, property condition, relocation plans, finances, and the market segment in which you are selling and buying.
When May Waiting Make Sense?
A short delay may be reasonable if your home needs important repairs, you need time to prepare financially, or current comparable sales do not support your desired price.
However, the decision should be based on a clear reason and a realistic estimate of the costs and benefits, not simply an expectation that mortgage rates will fall.
Compare a potential sale now with a later sale using current market data, expected ownership costs, and estimated proceeds.
How Do You Sell an Ashburn Home When Mortgage Rates Are High?
A higher rate market calls for careful preparation, accurate pricing, and a clear plan for marketing and negotiation.
How Should You Price the Home?
Start with recent closed sales that resemble your home in location, size, property type, condition, and features.
Then review active listings and pending sales to understand the competition. Asking prices provide context, but they do not prove what buyers will ultimately pay.
Your pricing strategy should reflect available evidence and your selling objectives, rather than an assumption that your home will appreciate by a particular amount.
How Should You Prepare the Property Before Listing?
Pre-Listing Checklist
- ✓Declutter and clean the main living areas.
- ✓Improve lighting and presentation.
- ✓Address visible maintenance issues.
- ✓Prepare outdoor spaces and entryways.
- ✓Gather relevant property information and Virginia disclosure forms.
- ✓Discuss whether staging or specific repairs are worthwhile.
Not every renovation provides a worthwhile return. Focus on improvements that make sense for your property, target buyers, and budget.
Should You Offer a Seller Paid Mortgage Rate Buydown?
It can help in some cases. A seller may offer a credit toward a temporary or permanent mortgage rate buydown, which can reduce the buyer's payment under the applicable loan terms. A permanent buydown uses discount points, which lower the rate in exchange for paying more at closing.
However, a buydown is not always better than a price reduction. Its value depends on the loan, lender requirements, credit amount, the buyer's expected holding period, and your net proceeds.
Compare the proposed credit with other options and confirm the structure with the buyer's lender before agreeing.
How Should You Evaluate the Entire Offer?
A strong offer includes more than the sale price. Financing conditions, contingencies, inspection requests, closing dates, and requested credits can all affect the outcome.
Compare the terms and estimated proceeds of competing offers before deciding how to respond.
What Does a Practical Selling Timeline Look Like?
Valuation and Strategy: Week 1
Review comparable sales, equity, pricing, and selling costs.
Preparation and Marketing Media: Weeks 2 to 3
Complete agreed preparation, photography, video, and drone footage.
Listing Launch and Showings: Around Week 4
Publish the listing and review buyer response.
Offer Review and Negotiation: Weeks 4 to 5
Compare offers, contingencies, credits, and closing terms.
Contract to Settlement: Weeks 5 to 9
Manage inspections, appraisal, financing, and closing steps.
This is an illustrative planning schedule, not a promise. The actual timeline depends on the property, preparation requirements, buyer financing, inspections, and contract terms.
For more detail, see our full guide to selling your home in Ashburn.
How Can You Protect Your Net Proceeds When Mortgage Rates Are High?
You cannot control national mortgage rates, but you can compare your selling costs and the services included in your listing agreement.
The listing fee is one part of the transaction. Other costs can include buyer agent compensation if agreed, settlement expenses, taxes, mortgage payoff, HOA charges, repairs, and negotiated credits.
What Does the 1.5% Full Service Listing Include?
The Jamil Brothers offer a full service listing option from 1.5%. The 1.5% listing-side fee is available on qualifying homes that sell for $500,000 or more. The advertised package includes:
- ✓4K HDR property photography and 4K media.
- ✓Drone aerial video where appropriate.
- ✓3D Matterport tour.
- ✓Full MLS marketing, with exposure on Zillow and Redfin.
- ✓Targeted social advertising.
- ✓Pricing guidance, partner-led offer negotiation, and contract to close support.
Arslan Jamil, Associate Broker®, ABR®, co-leads the team with Saad Jamil, and the program describes partner-led negotiation with direct access to both. The team is affiliated with Samson Properties.
Confirm the specific marketing deliverables, services, and eligibility in your listing agreement before signing. Our guide to what the 1.5% listing fee includes walks through the scope.
How Much Can You Save With a 1.5% Listing Fee?
On a $750,000 sale, the listing fee comparison is straightforward.
| Listing fee | Calculation | Amount |
|---|---|---|
| Illustrative 3% listing fee | 3% of $750,000 | $22,500 |
| The Jamil Brothers | 1.5% of $750,000 | $11,250 |
| Difference | 1.5% of $750,000 | $11,250 |
At the same sale price, the difference is $11,250 in listing fees.
This is a comparison with a hypothetical 3% listing fee, not a claim that every agent charges 3%. Commissions are negotiable and not set by law, services vary by agreement, and buyer agent compensation is separate from the listing fee.
Seller Savings Calculator
Select the price closest to your home to compare illustrative proceeds under a 3% listing fee and a 1.5% listing fee. The calculator starts at $750,000, near Loudoun County's September 2026 median sold price of $758,500 (NVAR).
Seller Savings Calculator
How much more could you keep with a 1.5% full service listing fee?
Select your Ashburn home's estimated value to compare illustrative proceeds side by side.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$7,500
Compared with a hypothetical 3% listing fee on a $500,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$11,250
Compared with a hypothetical 3% listing fee on a $750,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$15,000
Compared with a hypothetical 3% listing fee on a $1,000,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$22,500
Compared with a hypothetical 3% listing fee on a $1,500,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$30,000
Compared with a hypothetical 3% listing fee on a $2,000,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$45,000
Compared with a hypothetical 3% listing fee on a $3,000,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Illustrative 3% listing fee
1.5% full service listing fee
Listing fee difference
$60,000
Compared with a hypothetical 3% listing fee on a $4,000,000 sale at the same price. Not a quote or a guarantee of final proceeds.
Assumptions: 2.5% buyer agent compensation and 1% estimated closing costs are illustrative placeholders, not required or standard fees. Your own figures can be entered in a custom net sheet.
Not included: mortgage payoff, liens, repairs, seller credits, HOA charges, taxes, and any other costs or credits not shown above.
Estimates only. Commissions are negotiable and not set by law. Buyer agent compensation is separate and negotiable. The 1.5% listing-side fee applies to qualifying homes selling for $500,000 or more, under the signed listing agreement.
4K photography and media, drone video, a 3D tour, full MLS marketing, and partner-led negotiation are part of the advertised package. In a higher rate market, the listing fee is one of the few selling costs you can compare before you sign.
Listing fee difference
$11,250
1.5% versus a hypothetical 3% listing fee on a $750,000 sale at the same price
Why Compare the Service, Not Just the Fee?
A lower listing fee is only useful when you understand what services you receive.
The Jamil Brothers combine the 1.5% listing option with premium property marketing and partner-led negotiation. If your situation calls for a different structure, our flexible commission options explain the alternatives so you can compare costs and services before choosing representation.
When Does a Cash Offer Make Sense in a High Rate Market?
A cash offer may suit a seller who values speed or certainty more than achieving the highest possible sale price.
Because a cash purchase does not depend on the buyer obtaining a mortgage, it may avoid some financing related delays. However, cash offers can still include contingencies, inspections, or other conditions.
A cash offer may be worth considering if you are relocating quickly, selling an inherited property, managing a time sensitive move, or dealing with a property that needs significant work.
Potential Advantages of a Cash Offer
- ✓No buyer mortgage financing contingency, if the offer is structured without one.
- ✓Potentially fewer financing related delays.
- ✓Flexibility around the settlement date, depending on the buyer and agreement.
Potential Disadvantages
- ○The offer price may be lower than what a well marketed listing could achieve.
- ○There may be fewer competing buyers.
- ○Contract terms and buyer reliability vary.
Compare the net proceeds from a cash offer with a traditional listing rather than comparing headline prices alone. Our breakdown of what speed and certainty cost in Ashburn walks through the math.
You can also review your Ashburn cash offer options side by side with a listing plan.
Glossary: Mortgage Rates and Selling Terms
Rate lock in effect
When homeowners keep their current mortgage because replacing it with a new one could mean a higher rate.
Months of supply
An estimate of how long the available inventory would take to sell at the current sales pace.
Mortgage rate buydown
A structure in which eligible funds reduce the mortgage rate temporarily or permanently, subject to lender requirements.
Purchasing power
The amount a buyer can afford to borrow and spend at a given interest rate and monthly payment.
Net proceeds
The amount remaining after applicable selling costs, agreed compensation, credits, and mortgage payoff are accounted for.
Days on market
The number of days a property is listed before going under contract, as defined by the reporting source.
Contingent offer
An offer that depends on a stated condition, such as the buyer selling their current home.
Freddie Mac PMMS
Freddie Mac's Primary Mortgage Market Survey, which reports weekly national mortgage rate averages.
Full service listing
A listing arrangement covering the services specified in the listing agreement, which may include pricing guidance, marketing, negotiation, and transaction support.
Listing fee
The compensation agreed with the listing brokerage for its services. The amount and included services depend on the listing agreement.
Mortgage Rates and Your Ashburn Home Sale: What Sellers Should Know
Mortgage rates affect buyer affordability and may influence how buyers negotiate, but they do not independently determine your final sale price. In September 2026, Loudoun County's median sold price was $758,500 while closed sales declined 17.8% year over year (NVAR), which is why sellers need a current local assessment.
No one can predict where rates will go next. Waiting for lower rates may or may not improve your position, so your equity, moving plans, property condition, and ownership costs should guide the decision.
Before listing, review recent comparable sales, estimate your net proceeds, and understand the competition for your property.
See where your home stands against current Ashburn comparable sales and competing listings, then decide on timing with real numbers in hand.
Frequently Asked Questions
How do mortgage rates affect selling your home in Ashburn, VA?
Mortgage rates affect buyer affordability, demand, and negotiations. Higher rates can reduce the amount buyers can borrow and make them more payment sensitive, but they do not automatically lower every home's value. Pricing, condition, inventory, and local demand also matter.
Who is the best realtor in Ashburn, VA?
The right agent has relevant local experience, a clear pricing strategy, professional marketing, transparent fees, and strong communication. The Jamil Brothers' MLS records show 113 unique Ashburn closings, which makes them an ideal option. Ask every agent you meet what their fee includes and compare the agreements.
Does The Jamil Brothers' 1.5% listing fee include full service?
Yes. The advertised 1.5% listing fee option includes pricing guidance, premium marketing, negotiation, and transaction support. It applies to qualifying homes selling for $500,000 or more. You will get all the specific deliverables and services in your listing agreement.
Does the 1.5% listing fee include drone video and 4K media?
The advertised package includes 4K HDR photography and 4K media, drone aerial video, a 3D Matterport tour, and full MLS marketing. Confirm the specific deliverables for your property before signing the listing agreement.
Who leads a Jamil Brothers listing?
The Jamil Brothers Realty Group is a team affiliated with Samson Properties, led by Associate Broker Arslan Jamil and Saad Jamil. The program describes partner-led negotiation with direct access to both. Confirm the responsible broker and all fees in your agreement.
How much can I save with a 1.5% listing fee?
On a $750,000 sale, a 1.5% listing fee is $11,250, compared with $22,500 at 3%. That is an $11,250 difference in listing fees, assuming the same sale price. Buyer agent compensation and other transaction costs are separate.
Should I wait for mortgage rates to drop before selling my Ashburn home?
Not automatically. Lower rates could attract more buyers, but they may also encourage more homeowners to list. Your equity, timeline, carrying costs, and next purchase should inform the decision.
Do high mortgage rates lower home prices in Ashburn?
They can put downward pressure on demand, but prices also depend on inventory, property type, condition, and local buyer activity. Countywide figures cannot predict the value of every Ashburn property.
What is the mortgage rate lock in effect?
It describes homeowners who hesitate to sell because they would have to replace a low existing mortgage rate with a higher one. It can limit the number of homes coming to market, although the effect varies with local conditions.
What is the current mortgage rate in 2026?
Freddie Mac reported a 7.40% average 30 year fixed mortgage rate on October 15, 2026, up from 6.27% a year earlier. This is a national survey average, not a guaranteed rate for every borrower.
Is 2026 a good time to sell a house in Ashburn?
It depends on your property, finances, and plans. NVAR reported a $758,500 Loudoun County median sold price in September 2026, while closed sales fell 17.8% year over year. Use recent comparable sales and competing listings to assess your opportunity.
Can I offer a mortgage rate buydown to attract buyers?
Potentially. A seller paid buydown may lower a buyer's mortgage payment under the applicable loan terms. Compare the cost with a price reduction and confirm the structure with the buyer's lender before agreeing.
How long does it take to sell a house in Ashburn?
Loudoun County's average days on market was 31 days in September 2026 (NVAR). That is a countywide figure, not a guarantee for Ashburn. The full time from listing to closing depends on pricing, buyer financing, inspections, and contract terms.
Are cash offers better than listing when mortgage rates are high?
Not necessarily. Cash offers can offer convenience and reduce financing related uncertainty, but the price may be lower. Compare the complete terms and expected net proceeds before deciding.
If I sell now, can my buyer refinance when rates drop?
A buyer may be able to refinance later if they qualify and the available terms make sense. Future rates and refinancing eligibility are not guaranteed, so buyers should evaluate the original mortgage on its own merits.
Does selling and buying at the same time become harder when rates are high?
It can require more planning because you need to coordinate sale proceeds, financing, and moving dates. A contingent offer, rent back arrangement, or bridge financing may help in some circumstances, subject to the relevant terms and risks.
Mortgage rates and housing market statistics change over time. Countywide statistics are not individual property valuations, and savings examples are illustrative rather than guarantees. This article is general real estate information, not legal, tax, or lending advice. The Jamil Brothers Realty Group are real estate professionals, not attorneys, tax advisers, or lenders.
Explore More
DMV Real Estate Northern Virginia Loudoun County Ashburn Sell My Home Home Valuation Cash Offers Flexible Commissions Seller Net Sheet Buyer Strategy Agent Careers Get Licensed Jamil Academy ContactSources and Data Notes
Mortgage rates: Freddie Mac, Primary Mortgage Market Survey, national weekly averages for the week of October 15, 2026. Freddie Mac publishes new figures each Thursday.
Loudoun County market statistics: Northern Virginia Association of Realtors, Market Statistics: September 2026, published October 16, 2026, based on Bright MLS data, all property types.
Team figures: The Jamil Brothers Realty Group's own MLS records. These are a small sample, not a market report.
Listing service details: The Jamil Brothers Realty Group, 1.5% listing program and Flexible Commission pages. Services, eligibility, and fees are governed by the signed listing agreement.
Categories
- All Blogs (1120)
- Aldie (3)
- Ashburn (6)
- Buyer Guide (8)
- Buying a home (2)
- Buying Strategies (28)
- festivals (1)
- General Blog (64)
- Leesburg (5)
- Market Intelligence (29)
- Market Updates (8)
- Notable Properties For Sale (29)
- Real Estate Tips, News, and More (369)
- Seller Guide (2)
- Seller Guides (60)
- Selling Your Home (446)
- Sterling (6)
- Top Realtors in Northern Virginia (56)
Recent Posts
Message Sent!
Thank you for reaching out. Arslan & Saad have received your details and will be in touch shortly.
Need immediate assistance? Call or text 703-782-4830.